

This Week's Briefing
This week, AI's real money went almost entirely into things you can touch. The three largest confirmed primary-market deals were drones (Quantum Systems, $1.2 billion), embodied robotics (AI2Robotics, $735 million), and satellites (Chang Guang Satellite Technology, $694 million), with quantum computing, photonics, and humanoid robots crowding the rankings while pure software and pure models faded to the margins. Meanwhile, the exit gate opened for Chinese hard tech in force for the first time: 5 AI companies IPO'd this week, and 7 of 8 listing and pre-IPO events came from China. Unitree received its STAR Market registration approval in just 73 days, and Momenta filed for a Hong Kong IPO. The money coming in is buying hardware, and the doors opening on the way out are for hardware too. This week, physical AI is winning on both ends.
I. Market Watch
This section is a curated selection plus SVTR analysis. The full rolling event stream across four market-event categories (funding / IPO / M&A / fund closes) updates in real time at AI Venture Daily #164.
① IPOs and Listings
| Company | Raise | Listing Venue & Focus |
|---|---|---|
| Momenta | $751M | Hong Kong Stock Exchange · Autonomous Driving |
| Unitree Robotics | TBD | STAR Market · Humanoid / Quadruped Robots |
| IQM | $234M | NASDAQ (IQMX) · Quantum Computing (Finland) |
| Crealights (海光芯正) | $181M | Hong Kong Stock Exchange 01191 · AI Chips |
| SiliconFlow (硅基流动) | TBD | Hong Kong Stock Exchange · LLM Inference Cloud |
| Benmo Technology (本末科技) | Cleared hearing | Hong Kong Stock Exchange · Direct-Drive / Wheel-Legged Robots |
SVTR take: Five AI companies completed IPOs this week. Add in Kling, the AI video model spun off from Kuaishou, which closed a pre-IPO round of nearly $3 billion at a post-money valuation of about $18 billion (see this week's flagship Signal #23), and 7 of 8 listing and pre-IPO events came from China. Benmo Technology (direct-drive wheel-legged robots) cleared its Hong Kong Stock Exchange hearing this week and entered the countdown to its offering, and the queue of robotics companies heading to market keeps growing. The most emblematic case is Unitree: it received STAR Market registration approval in 73 days, the first time a humanoid and quadruped robot maker has completed registration on China's main board. This time, the exit gate didn't open for large models. It opened for robotics, AI chips, inference clouds, and other Chinese hard tech.
② Key Funding Rounds (Confirmed This Week)
| Company | Round | Amount | Lead Investors / Focus |
|---|---|---|---|
| Quantum Systems | Series D+ | $1.2B | Blackstone, Airbus, Advent|Military Drones (Germany) |
| Together AI | Series C | $800M | Aramco, Nvidia, General Catalyst|AI Inference Cloud |
| AI2Robotics (智平方) | Strategic | $735M | Embodied AI / General-Purpose Robotics (China) |
| Chang Guang Satellite Technology (长光卫星) | Undisclosed | $694M | Changfa Group, Lushi Investment|Satellite Constellation (China) |
| Etched | Strategic | $500M | Peter Thiel, Jane Street|Transformer-Specific Chips |
| Spirit AI (千寻智能) | Series A+ | $208M | Embodied AI (China) |
| VAST | Series A3 | $150M | Geely Capital|Commercial Space Station |
| SpinQ (量旋科技) | Series D+ | $141M | CICC Capital, Shanghai Semiconductor Industry Investment|Quantum Computing (China) |
| TwelveLabs | Series B | $100M | NEA, NAVER, Amazon, Nvidia|Video Understanding Models |
SVTR take: Almost all the new money in the primary market flowed into atoms: drones, humanoid robots, satellites, quantum, photonics. Of the top ten confirmed rounds, only Together AI (inference cloud) and LeapXpert (enterprise messaging) were pure software; the other eight were tangible hardware. The single largest round, Quantum Systems' $1.2 billion, was co-led by Blackstone and Airbus and channeled into defense-grade drones, the sharpest single data point in this week's physical-AI storyline.
③ Strategic M&A
| Acquirer | Target | Consideration | Notes |
|---|---|---|---|
| Schneider Electric | Cognite | $3.1B all-cash | Industrial AI software folded into AVEVA |
| Aikido Security | Root.io | ~$70–100M | Open-source dependency security folded into an AppSec platform |
| Saltroad | Ogma | Undisclosed | Turned around and did an acquisition the same day it closed new funding |
SVTR take: Schneider Electric's $3.1 billion all-cash purchase of industrial data platform Cognite, folded into AVEVA, is a bet on industrial AI software that plugs directly into factories and power grids. Even the M&A side of the market is moving toward things that can be deployed on the production line. Industrial giants are no longer building AI in-house; they're buying finished industrial AI capability wholesale into their operational technology stack. That runs in the same direction as this week's primary-market theme of buying hardware, buying the physical.
④ VC Fund Closes
| Fund | Size | Status | Focus |
|---|---|---|---|
| Copper Sky Capital Fund II | $300M | Raising | Jack Selby (Thiel network); hardware / defense deployable outside Silicon Valley, based in Arizona |
| Magnify Ventures Fund II | $46.6M | Final close | "Care economy" AI: household tools, health, family financial infrastructure |
SVTR take: Both new funds are betting against consensus. Copper Sky is run by Thiel-network figure Jack Selby and explicitly targets hardware, including defense, that can be manufactured outside Silicon Valley, New York, and Boston and deployed in Arizona; this week's $500 million Etched round is one of its portfolio companies. Magnify has put its entire seed fund behind household and "care economy" AI. Beyond the hottest robotics and hardware bets, capital is also hunting for mismatched supply at both ends.
II. VC Take
One-line verdict: This week, capital bought atoms, not bits.
Supporting data (SVTR AI Venture Database #164): 86 confirmed funding rounds this week, 59 with disclosed amounts totaling $7.33 billion. Eight of the top ten confirmed rounds were hardware: drones, humanoid and embodied robotics, satellites, quantum, AI chips. Only Together AI and LeapXpert remained pure software. On the exit side, 5 IPOs plus Kling's pre-IPO round meant 7 of 8 came from Chinese hard tech. Money coming in is buying robots and photonics; the exit gate is being held open for hard tech listing on China's A-share and Hong Kong markets. Both ends of AI capital turned physical this week. The model layer is no longer the asset being bet on, nor the one being exited.
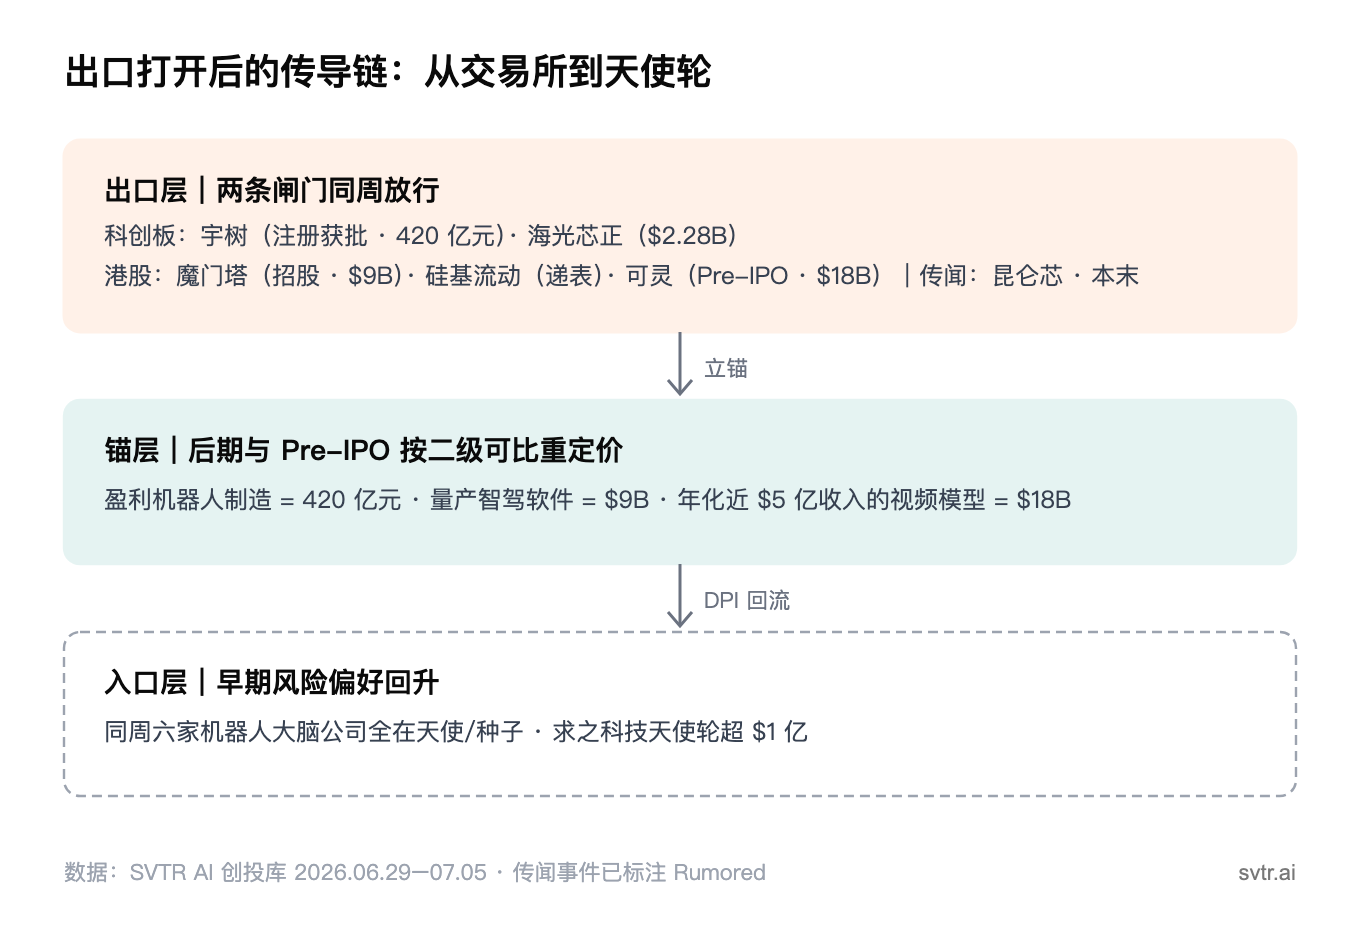
For the China-side unpacking of this "turning physical" thread, see this week's flagship Signal #23: The Exit Gate Opened, Every Pricing Anchor Has to Move: Chinese AI capital closed its loop for the first time, and the exit has become scarcer than money itself.
III. Community Pulse
SVTR held an AI venture meetup this week. Among the 66 self-registered attendees were investors from Matrix Partners China, CITIC, and Alibaba, sitting alongside tarot readers and fortune-telling practitioners. On stage, Timing (顺时) broke fortune-telling down into two layers, a deterministic algorithm plus large-model output, and built an emotion-driven business off a Reddit cold start. See the full recap in the Editor's Picks section below.
New founders joining the community this week skewed heavily toward hardware: Guangdian Zhichuan (光点智传, optical communications), Cambridge Mechatronics (UK, SMA micro-actuators), and Xinhe Optoelectronics (芯河光电, optoelectronics) were all optoelectronic or electromechanical hardware plays, alongside a robotics ecosystem player from the AI Robotics Alliance of America. On the investor side, early-stage financial investors focused on AI made up most of the group.
This supply-and-demand picture lines up with this week's market events: the founders flowing into the community are building optoelectronic and electromechanical hardware, and primary-market money is buying robots, photonics, and chips. This week, demand and capital point to the same place: physical AI.
IV. Editor's Picks
The Exit Gate Opened: Chinese AI Capital Closes Its Loop for the First Time (Signal · Forward-Looking Signal)
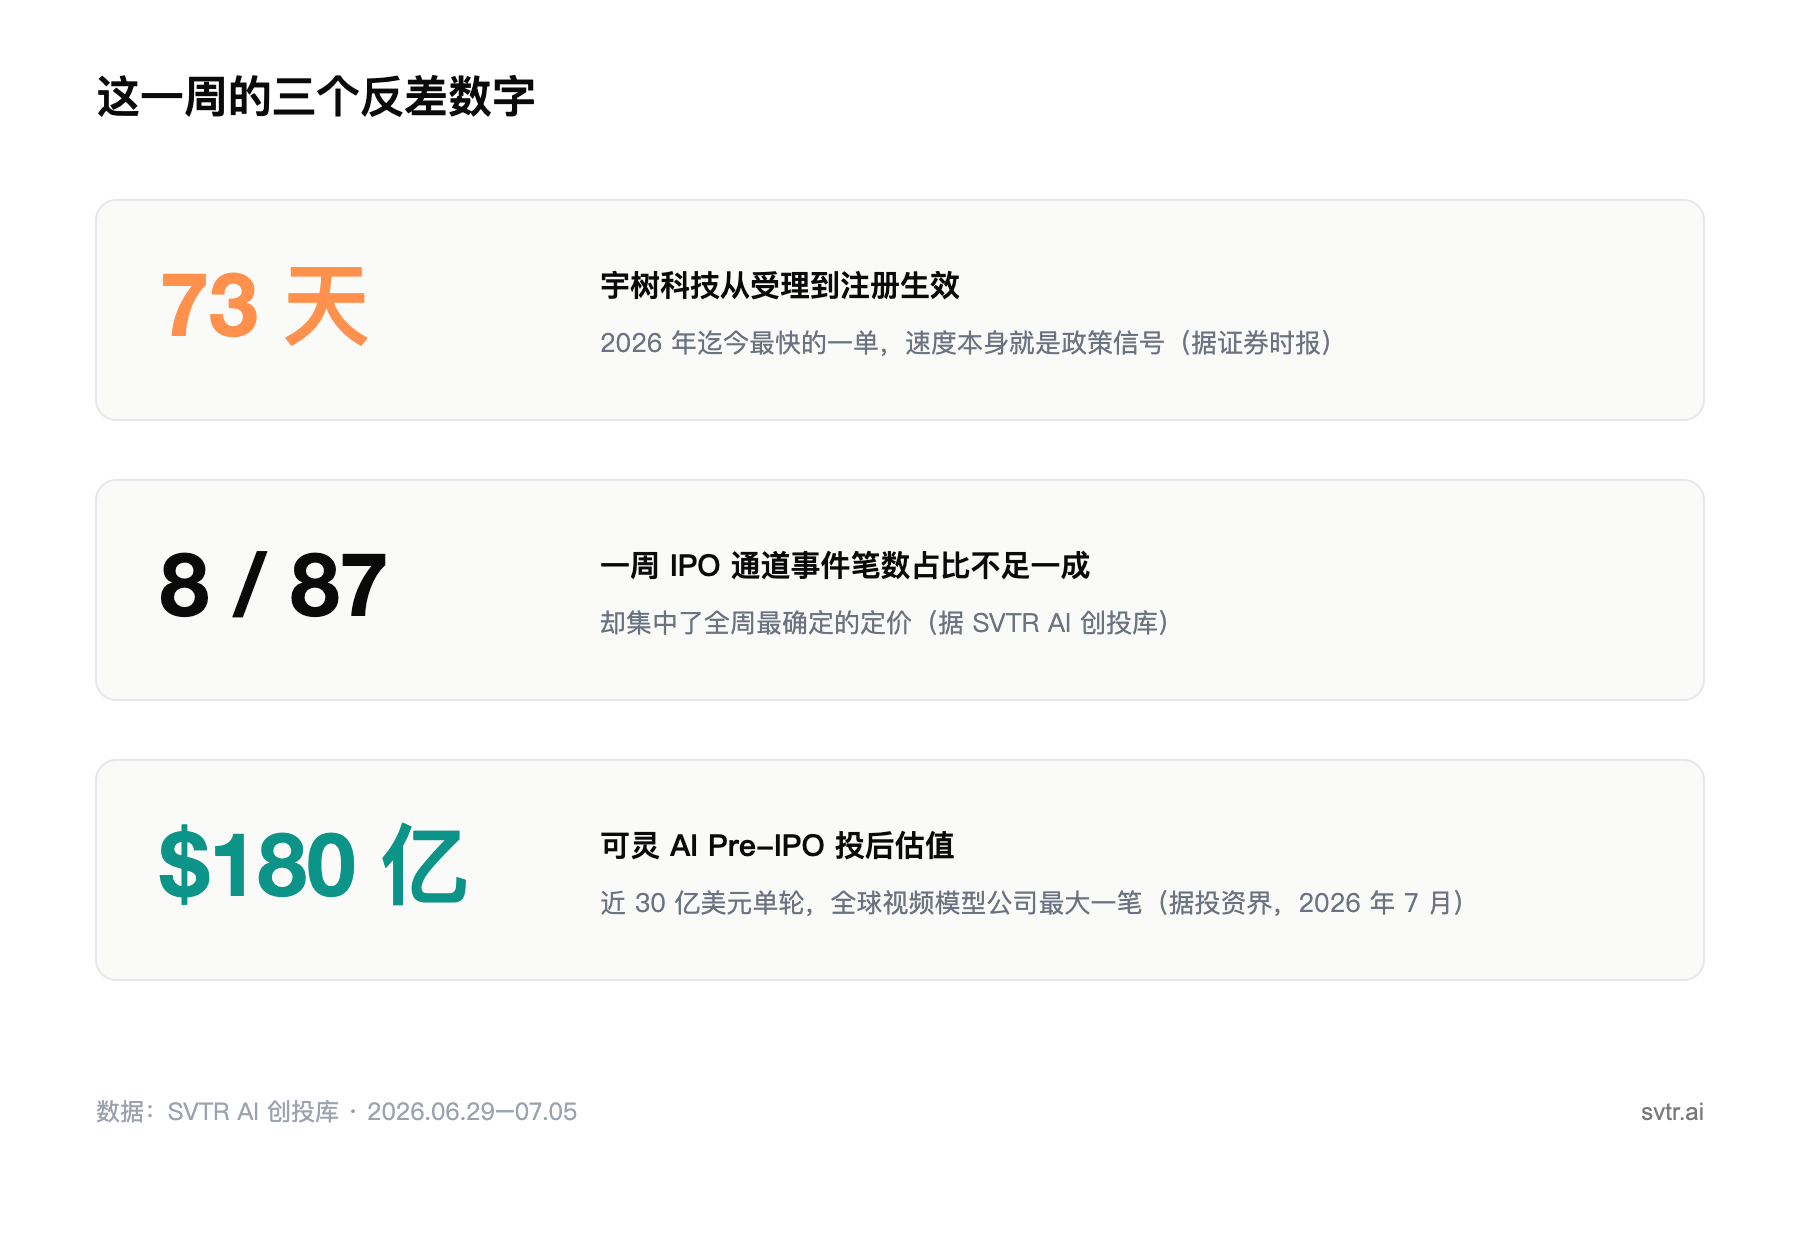
In a single week, the SVTR AI Venture Database logged 8 IPO and pre-IPO channel events, 7 of them from China. Unitree received STAR Market registration approval in 73 days, Momenta filed for a Hong Kong IPO, and Kling closed a pre-IPO round of nearly $3 billion at a post-money valuation of roughly $18 billion. SVTR's read: the scarce resource in China's AI primary market is shifting from money to exits, and once the exit anchor is established, the pricing logic of the entire primary market gets rewritten. This is the source thread for this week's VC take.
Hard-Tech VCs and Fortune Tellers in the Same Room: Timing AI's Emotion Business (Recap · Venture Meetup Recap)
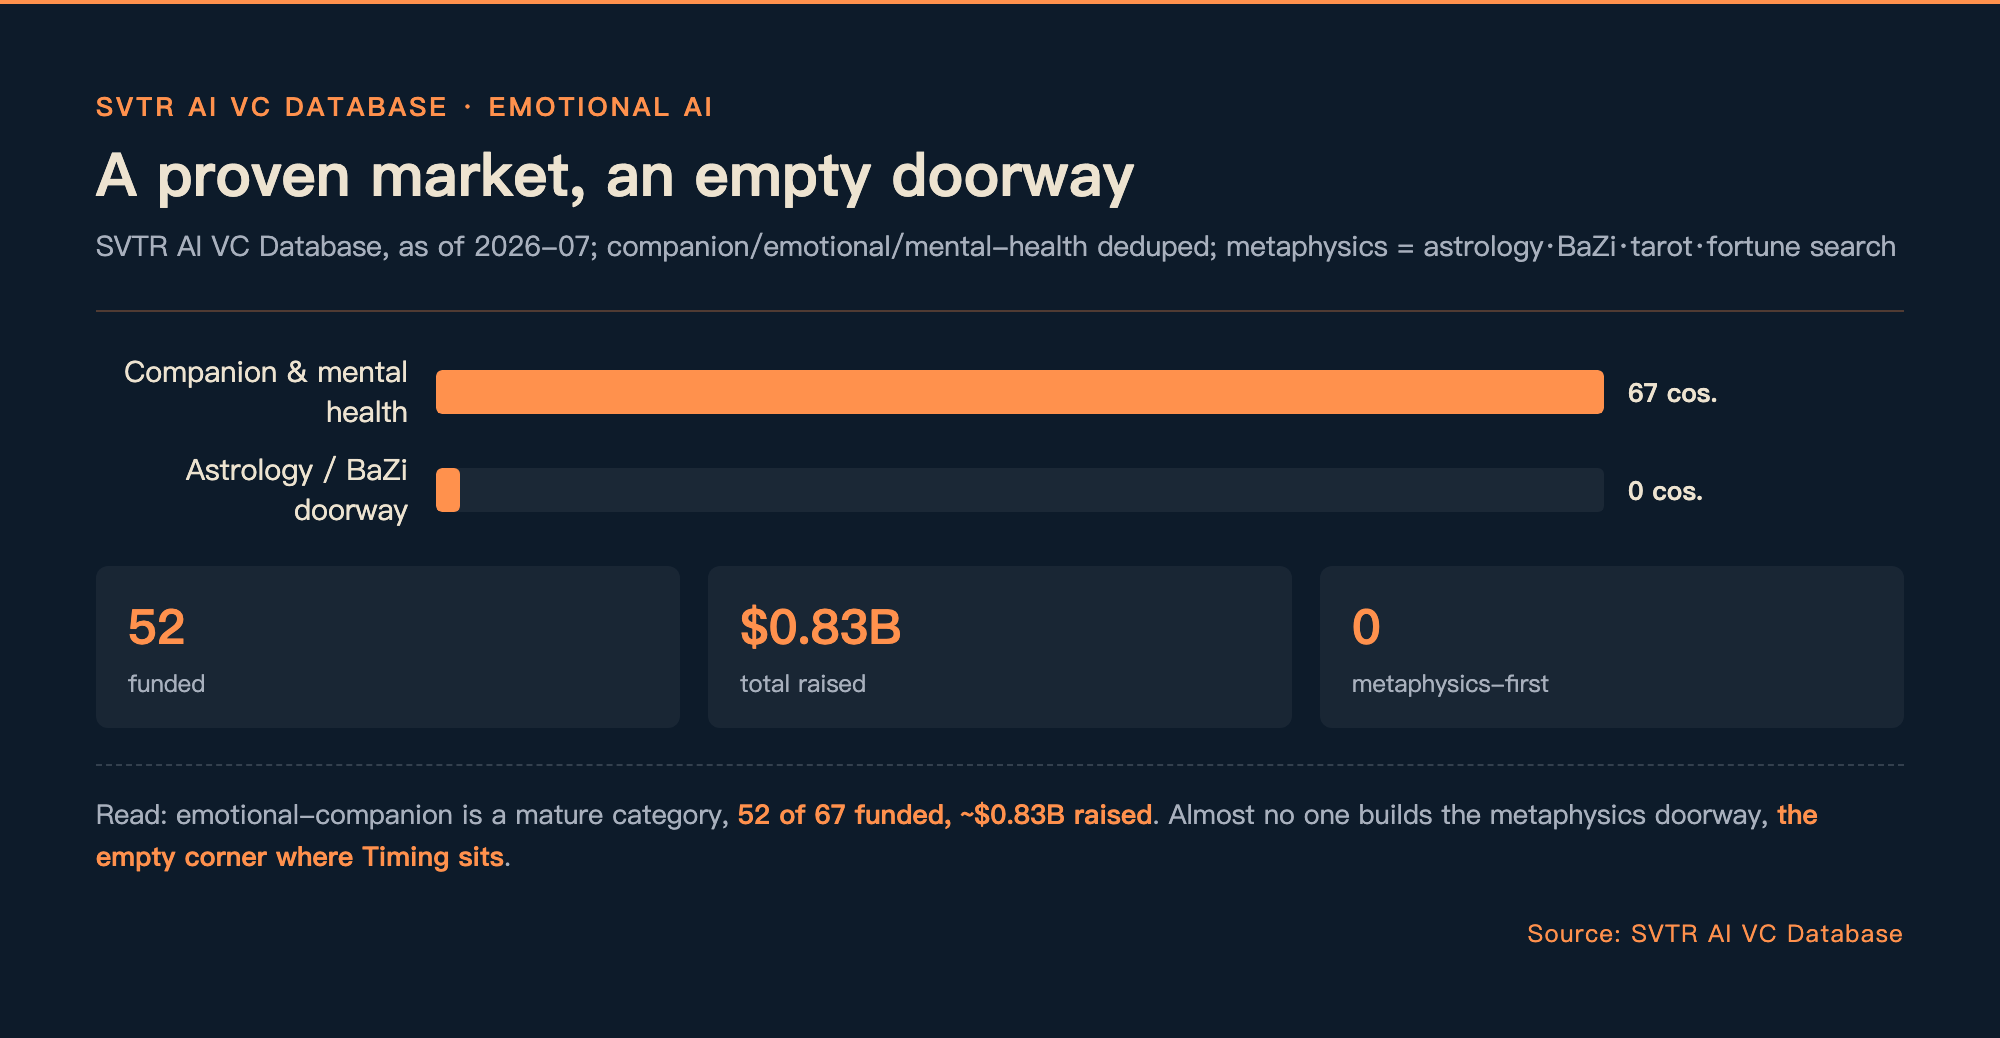
A firsthand recap of this week's SVTR AI venture meetup: among the 66 self-registered attendees, investors and fortune-telling practitioners shared the room. Timing broke Chinese astrology and birth-chart reading down into two layers, a deterministic algorithm plus large-model output, and built a paying user base off a Reddit cold start (per the founder, not independently verified). SVTR's read: the emotional-companionship category is already validated, but metaphysics as an entry point remains nearly untouched, a contrarian sample of consumer-AI cold starts.
VC Content's Moat Is Structure, Not Volume (Thesis · Investment Thesis)
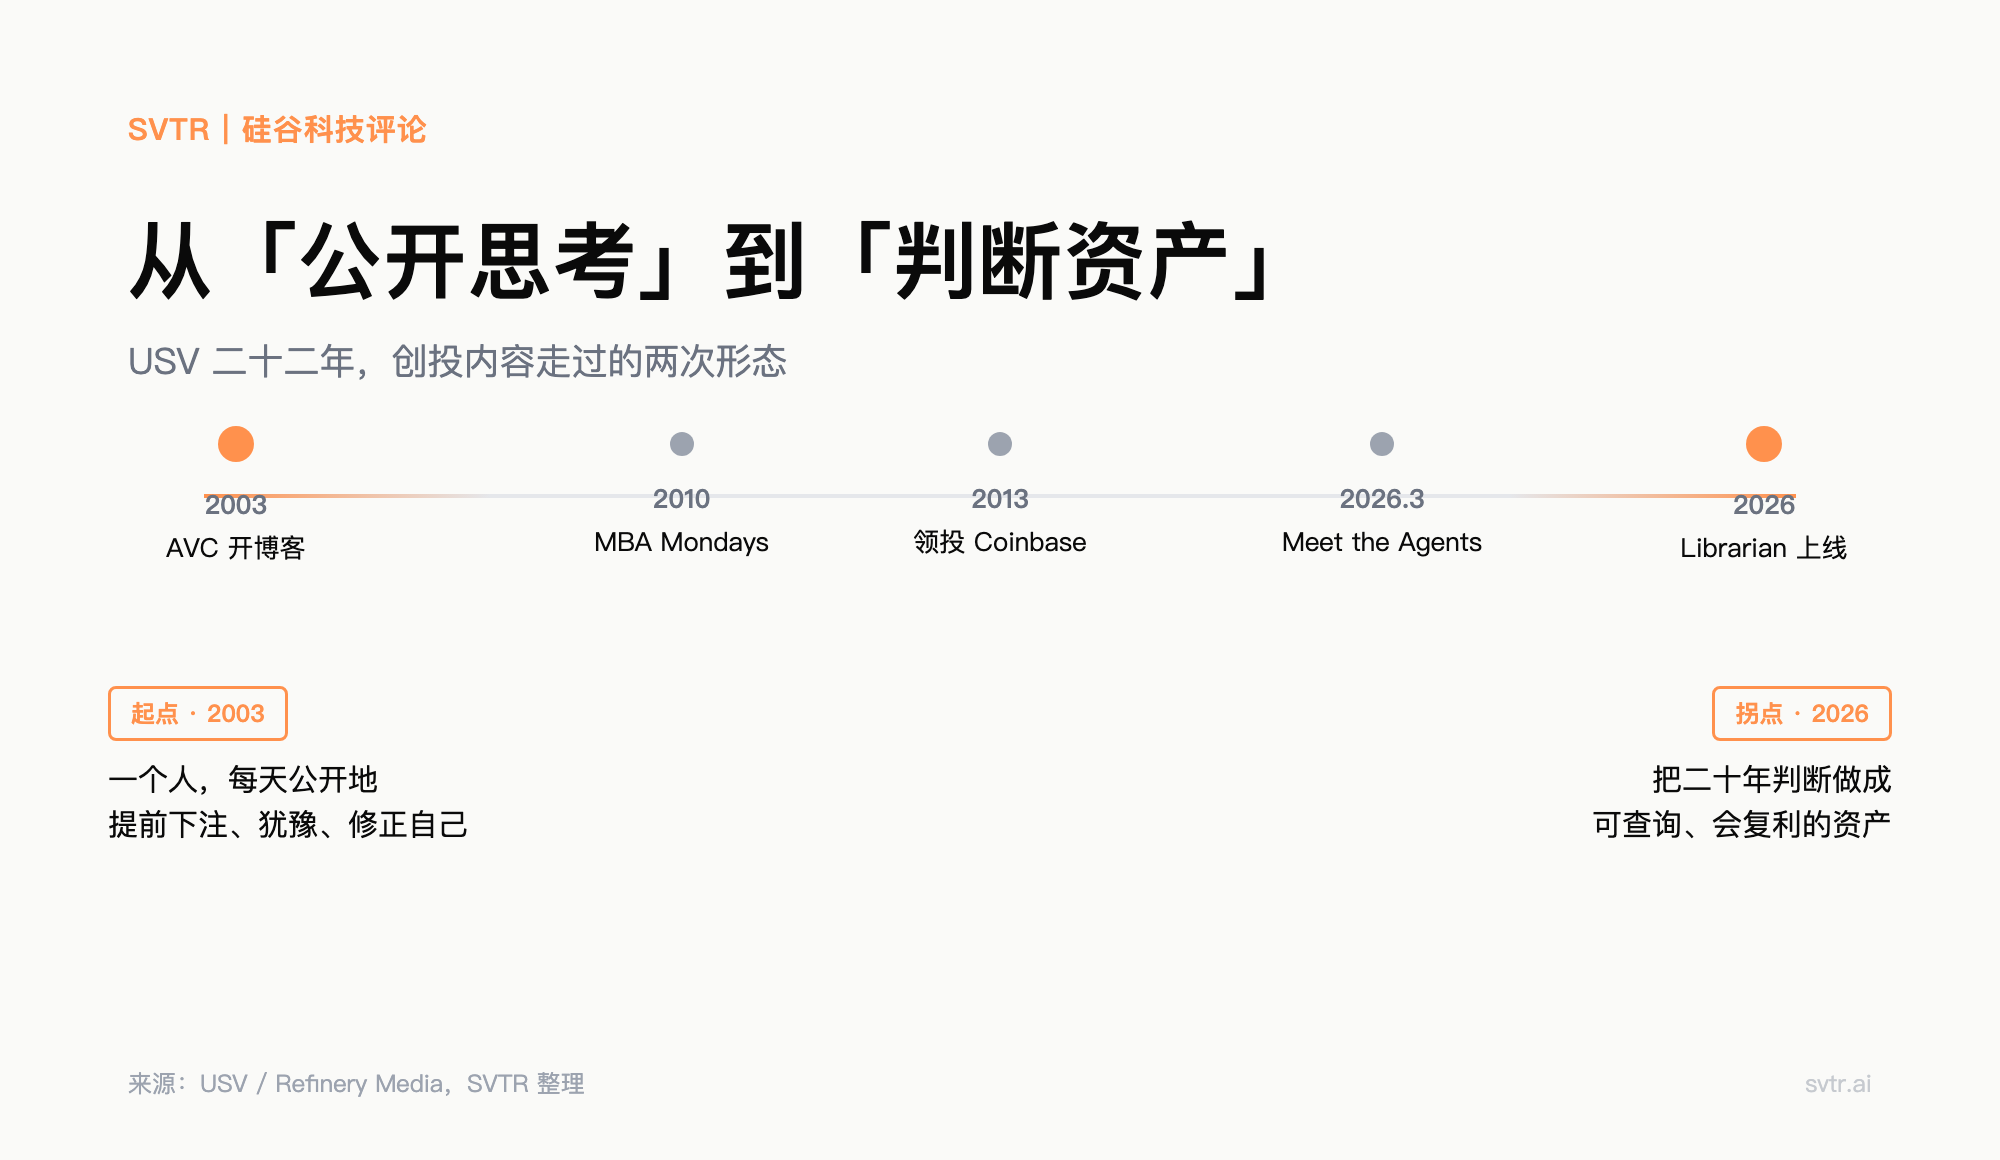
Venture firms worldwide have copied "doing content" down to blogs, podcasts, and weekly shows, but by 2026 USV has already moved on, turning two decades of judgment into a queryable, compounding asset. SVTR's read: the moat in content was never output volume. It is the structuring of judgment, and China has almost none of that asset.
V. Upcoming Events
AGI Summit 2026 (GenAI Summit SF)
Date: 2026-07-18 to 07-19 (PDT)
Location: Palace of Fine Arts, San Francisco
Tickets: Paid (includes an invite-only founder × investor dinner, price undisclosed)
SVTR score: 7.5/10
The most complete event in this window for scale and VC dealmaking: 300+ early-stage company booths and Main Stage startup pitches to investors.
SF AI & ML Startups × Investors Networking Mixer
Date: 2026-08-04 (PT)
Location: Upcider, 1160 Polk Street, San Francisco
Tickets: Free (one drink purchase required on site)
SVTR score: 7.0/10
Hosted by The Founders Club, with dense investor × founder matchmaking, a 1-minute pitch segment, and a low, free barrier to entry.
VI. Capital Map
This week's data and visualizations are live at AI Venture Daily #164: a daily rolling event stream plus sector / active-investor / by-stage funding charts, drawn from the same source and methodology as this section. Only the Top 10 and three data-driven takeaways are excerpted here.
This Week's Top 10 Funding Events (Confirmed Rounds, by Disclosed Amount)
| # | Company | Amount | Round / Focus |
|---|---|---|---|
| 1 | Quantum Systems | $1.2B | Series D+ · Military Drones |
| 2 | Together AI | $800M | Series C · AI Inference Cloud |
| 3 | Momenta | $751M | IPO · Hong Kong Stock Exchange · Autonomous Driving |
| 4 | AI2Robotics (智平方) | $735M | Strategic · Embodied Robotics |
| 5 | Chang Guang Satellite Technology (长光卫星) | $694M | Undisclosed · Satellite Constellation |
| 6 | Etched | $500M | Strategic · Transformer Chips |
| 7 | IQM | $234M | IPO · NASDAQ · Quantum |
| 8 | Spirit AI (千寻智能) | $208M | Series A+ · Embodied Robotics |
| 9 | Crealights (海光芯正) | $181M | IPO · Hong Kong Stock Exchange · AI Chips |
| 10 | LeapXpert | $180M | Undisclosed · Enterprise Messaging AI |
Note: Unitree's STAR Market IPO and Benmo Technology's Hong Kong Stock Exchange hearing (amounts undisclosed for both) are not counted in this amount ranking; this table and the online charts count only confirmed rounds.
Three Takeaways From This Week's Data:
- Physical AI sweeps the top ten. Eight of the top ten confirmed rounds are hardware (drones, humanoid and embodied robots, satellites, quantum, AI chips); only Together AI and LeapXpert remain pure software. Capital's main battleground has shifted from bits to atoms.
- Early stage still dominates. Of the 86 confirmed rounds, 65% are seed / angel / Series A (including pre-seed), with growth-stage rounds (B, C, D and beyond) making up less than a fifth combined. China's early-stage factory for robotics and hard tech is closing deals at speed.
- China: many and scattered; overseas: few and large (this week's sample, not a long-term ranking). By deal count, the leaders are early-stage Chinese institutions (GL Ventures, HongShan, Puhua Capital, Jinpu Investment, and Qingsong Capital, each with 3 deals). By check size, it's the opposite: this week's largest rounds were all led by overseas institutions. Blackstone and Wellington co-led Quantum Systems' $1.2 billion round, Nvidia and General Catalyst backed Together AI's $800 million round, and Radical Ventures backed Etched's $500 million round. Chinese institutions are writing many small early hard-tech checks; overseas institutions are making fewer, much larger bets.
Note: Visit SVTR's official website (svtr.ai) or contact WeChat pkcapital2023 for the full weekly report and project details.