

Weekly Highlights
AI venture capital pricing power is being reallocated this week. On the import side, top-tier funds are no longer competing for exclusivity: nearly half of the confirmed rounds this week were led by two or more institutions, with the scarcity of shares pushing star rounds from exclusive capture to shared risk. On the export side, domestic AI chip and large model companies are collectively shifting toward the public market, with Muxi and Moonshot AI both advancing their Hong Kong IPO plans. Big money is highly concentrated in three hard tech sectors: embodied intelligence, custom chips, and security and defense. Meanwhile, Chinese state capital is directing funds to the base of the hard tech supply chain through specialized industry chain funds. Joint lead investment, hard tech competition for stakes, and state capital sinking to the base are the three main themes of this week.
SVTR Private Signal · Not Investment Advice
This week's spotlight: Sierra (★ Evaluated, acquired Takeoff) · Moonshot AI (advancing Hong Kong IPO) · Etched (★ Evaluated, $300M Series C). Full list available at AI Venture Daily.
I. Market Observations
① IPO / Listing Updates
| Company | Update | Focus |
|---|---|---|
| Muxi (Sci-Tech Innovation Board 688802) | Advancing Hong Kong IPO (A+H) | AI Chip (China) |
| Moonshot AI | Initiating Hong Kong IPO | Large Model Kimi (China) |
Comment: Domestic AI assets are densely knocking on the door of the Hong Kong market. The GPU manufacturer Muxi is advancing A+H, which is already listed on the Sci-Tech Innovation Board, and Moonshot AI, the parent company of Kimi, has also initiated its Hong Kong IPO. The signal aligns with this week's Thesis Li Liang's Closed-door Talk: NVIDIA is Digging Its Own Grave: domestic computing power is shifting from 'buying NVIDIA' to 'building chips and listing on its own,' and the public market is the testing ground for this path change.
② Key Fundraising Rounds (Confirmed This Week, by Disclosed Amount)
| Company | Round | Amount | Lead Investor | Focus |
|---|---|---|---|---|
| Atoms | Undisclosed | $1.7B | Andreessen Horowitz (Uber, Bain also invest) | Robotics / Industrial Automation (US) |
| CuspAI | Series B | $450M | Kleiner Perkins, NEA (Bezos Expeditions also invest) | AI Material Discovery (UK/US) |
| Meshy | Series B | $400M | IDG, Sequoia, Monolith | 3D Generation AI (China/US) |
| Etched | Series C | $300M | Sequoia, Andreessen Horowitz | Custom Inference ASIC (US) |
| Glow | Series A | $180M | Sequoia, Cyberstarts, Greenoaks | Internal Threat Monitoring (US) |
| Cathedral | Undisclosed | $160M | Andreessen Horowitz, Sequoia | Military Cyber Warfare AI (US) |
| Humanoid | Series A | $152M | Prime Movers Lab | Humanoid Robot Logistics |
| Candid Health | Series D | $120M | Sixth Street Growth | Healthcare Billing Automation (US) |
| Yuzhou Tech | Early Stage Consolidated Disclosure | $80M | Sequoia China, IDG, Yunchu Capital | Hard Tech (China) |
| Neo | Series A | $75M | Andreessen Horowitz, Bessemer | AI Agent Management (US) |
Comment: What stands out most on this list is not the amount, but the arrangement of lead investors. Top-tier funds a16z and Sequoia are side by side in Etched (Series C of $300M, post-money valuation of $10.3B) and [Cathedral], while Meshy (nearly $400M, post-money valuation of $1.5B) and [Glow] each have three lead investors. Memory Tensor is jointly invested by Huawei Hahuo, Honor, SenseTime, and Shenzhen State Capital. The scarcity of shares has turned 'competing for exclusivity' into 'sharing the table.' In terms of amount structure, the largest single round Atoms (Travis Kalanick's robotics company, $1.7B) has pushed robotics and industrial automation to the top, followed by [CuspAI $450M] and [Etched and Meshy], making embodied intelligence, materials, and computing infrastructure the three major fund-raising areas this week.
③ Ongoing Fundraising (Rumors / Not Closed)
| Company | Amount | Investors | Focus |
|---|---|---|---|
| Genesis AI | ~$500M Series A | Premji Invest (reporting lead), HSG | Robotics Foundation Model |
| Mistral AI | Strategic Investment | Samsung Electronics | Large Model |
- All above are rumors / under discussion, not closed yet.*
Comment: The un-closed startup fundraising this week is concentrated in robotics foundation models and large models. According to [Bloomberg], Genesis AI is in talks for about $500 million at a $3 billion valuation to build a robotics foundation model, and Samsung is planning a strategic investment in Mistral. Capital is still stockpiling ammunition for the next round of model and embodied intelligence arms race, but all are stuck in the not-closed stage, with both hesitation and FOMO coexisting.
④ Strategic Acquisitions
| Acquirer | Target | Consideration | Type |
|---|---|---|---|
| Einride | Flipturn | ~$38.4M (all stock ADS) | First acquisition after listing, autonomous freight |
| Sierra | Takeoff | Undisclosed | Acquired from autonomous AI agent runtime |
| Cognition | The Interaction Company | ~$100M | Acquired AI programming / interaction team |
| Midjourney | Co-Star | Undisclosed | Acquired generative AI capabilities |
- There is also a rumor that Stripe is planning to acquire OpenRouter for about $10B (WSJ), but the amount and whether it is closed are not officially announced.*
Comment: The main line of M&A is the integration of AI agent infrastructure by industry leaders. According to Sierra's official announcement, it acquired Takeoff to supplement long-term autonomous AI agent runtime; Cognition acquired The Interaction Company's interaction team. Application layer leaders are building the foundation of autonomous AI agents, and when they can't get the lead investment, they directly buy the team into their bodies, which is the same logic as the group strategy in confirmed rounds this week.
⑤ VC Fund Raising
| Fund | Size | Status | Strategy |
|---|---|---|---|
| Khosla Ventures (three new funds) | Up to $5.5B | Under discussion | AI / Deep Tech, covering seed / early / growth |
| Dimension Fund III | $800M | Closed | Science × Computing, 60% larger than the second round |
| Sichuan Changshi Hard Tech Fund III | ¥1.275B (approx. $177M) | Closed | Fusion / Quantum / Embodied Full Industry Chain |
| Shanghai Kala AI Venture Fund | Committed ¥220M / Target ¥600M | Established | Early Growth in AI (Lakala Group) |
| SuperCharger Ventures Fund I | €10M | Raising | EdTech / Future Work |
| Jinfly AI Science and Technology Fund | ¥500M | Raising | Local State Capital Guidance |
Comment: The fundraising logic between the US and China is diverging. Dollar funds are betting on big themes: according to TechCrunch, Dimension's third fund of $800M, it focuses on 'Science × Computing,' and Khosla is even more aggressive with up to $5.5B. Chinese state capital, on the other hand, is directing funds to the base of the supply chain through industry chain funds: according to Investor's Network, Sichuan Changshi Hard Tech Fund III, it follows the Founders Fund model to cover fusion, quantum, embodied intelligence, and AI infrastructure. One invests in 'themes,' the other in 'chains.'
II. Venture Capital Analysis
One-sentence judgment: Top-tier funds are no longer competing for exclusivity, and the exclusive dividend is being replaced by the group strategy of co-leads.
According to this week's Signal Top-tier Funds No Longer Competing for Exclusivity: Nearly Half of This Week's AI Fundraising is 'Co-Lead': of the 63 confirmed financings in SVTR's AI venture database #167, nearly half were led by two or more institutions. Meshy (IDG, Sequoia, Monolith), Glow (Sequoia, Cyberstarts, Greenoaks), Cathedral (a16z, Sequoia), Etched (Sequoia lead, a16z follow-on), and Memory Tensor (Huawei Hahuo, etc.) are all exceptions.
We judge that in the star rounds with oversubscription, the scarcity of shares and the risk-sharing mechanism have led top institutions to shift from 'exclusive capture' to 'sharing the table,' and the exclusive logic of investing in people rather than projects is failing. This week's Sarah Guo's bet in Profile is the other side of the same coin: when the lead investment seats of top projects are priced up and occupied by groups, independent financial VCs either accept diluted shares or simply bet the entire fund on the 'opposite of the big tech's all-in' strategy.
III. Community Dynamics
The new entrants to the community this week are highly aligned with the market's main themes, with the supply side continuing to be biased toward 'hard' and 'embodied' areas. On the founder side: accelerating the evolution of robot bodies that have reached Series B, Haili Computing for computing power, Verum for AI agents, and Fox Star High and Aident AI for smart hardware. On the investment side, institutions like Geek Ventures and QD Capital have entered, focusing on AI and embodied intelligence. The supply side is bringing in robots, computing power, and AI agents, aligning with this week's primary market 'embodied intelligence and chips leading.' Founders looking to bring robot projects to Silicon Valley for roadshows can directly refer to the first event announcement below.
This section also has a recently concluded AI Venture Meeting · Psyrene: an online closed-door meeting on July 24, discussing how to enter the field of psychiatric medication adherence and turn 'taking medicine on time' into an active care system, as well as the mass production and export of medical hard tech under the Li Zexiang system. The full recap is available at "Almost 700 AI Healthcare Companies, Almost No One is Doing 'Taking Medicine on Time'".
IV. Event Announcements
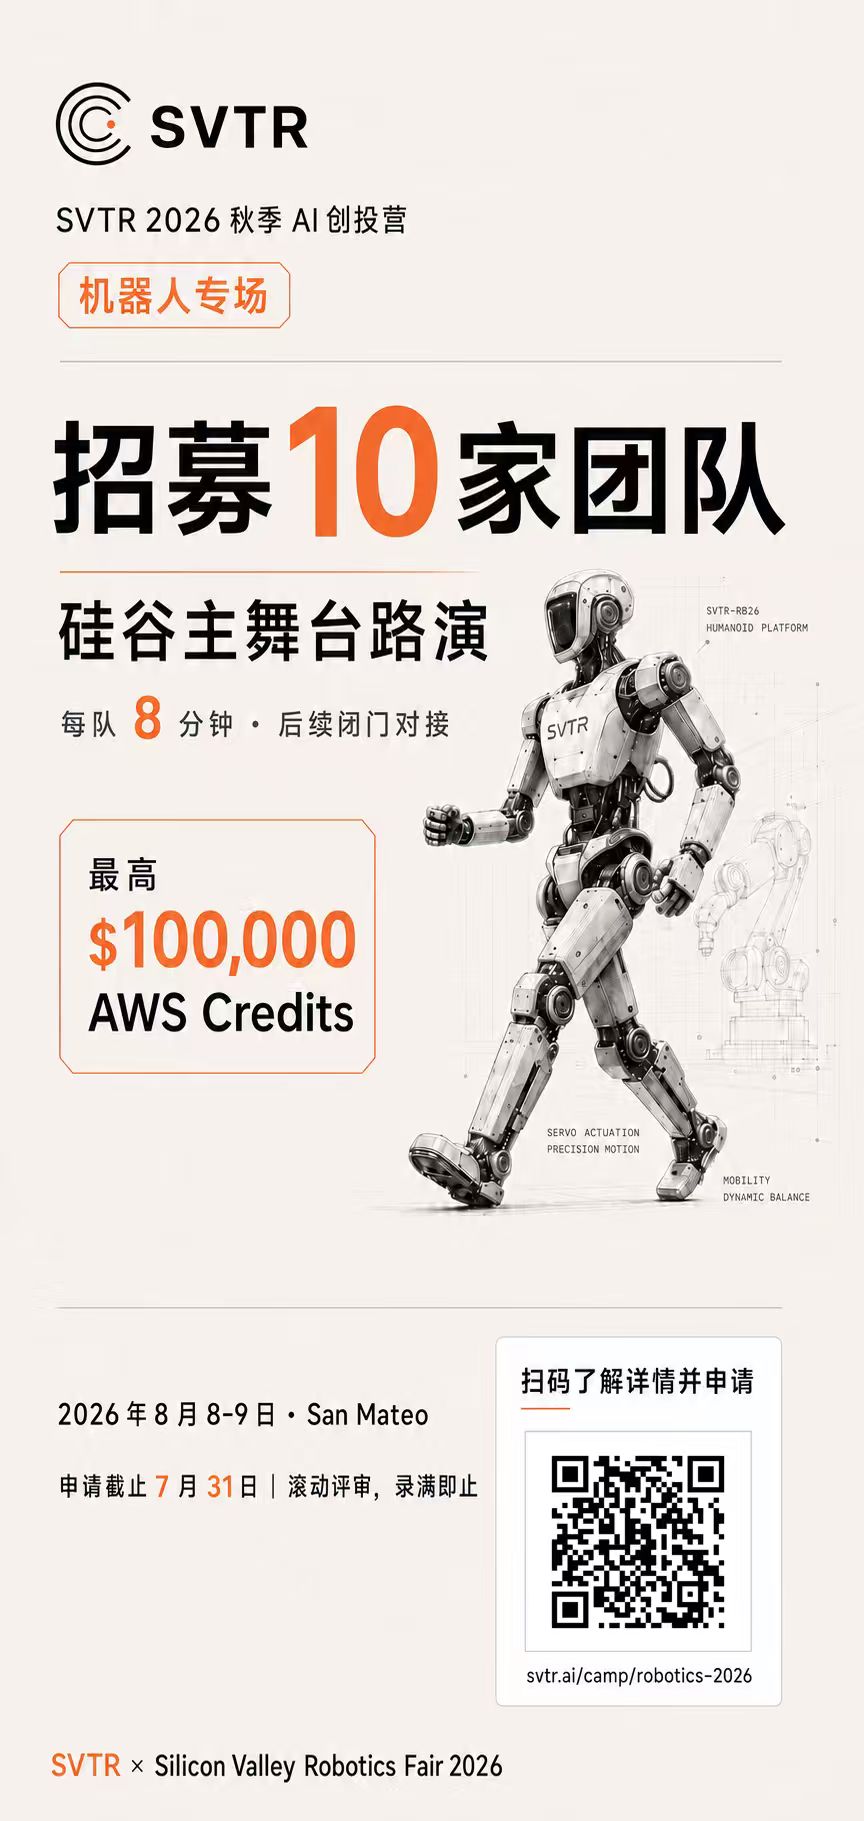
SVTR 2026 Autumn AI Venture Camp · Robotics Special Session (Hosted by this community)
Date: August 8 to August 9 (Pitch Day on August 9) Location: San Mateo County Event Center, California Target: AI Robotics, Embodied Intelligence, and Physical AI Teams, 10 slots Support: On-site pitch at the top robotics conference in Silicon Valley, investor matching, and up to $100K AWS subsidy (application deadline July 31)
SVTR's Autumn Venture Camp's first session is the Robotics Special Session, directly targeting the embodied intelligence chain that capital has heavily invested in this week.
Date: August 1 to August 2 (PT) Location: University of California, Berkeley (Live Stream Free) Ticket: Paid (In-person about $499, online free with registration) SVTR Rating: 8.0/10
Hosted by Berkeley RDI, with speakers such as Andrej Karpathy, Andrew Ng, Ali Ghodsi, Martin Casado (a16z), and Alfred Lin (Sequoia), the theme aligns with this week's 'who secures a round of capital' agentic AI main line.
V. Capital Map
Note: Genesis AI's $500M Series A is a rumor and not included in the above statistics; Crypto.com's $400M is a strategic investment by Citadel, included in the overview card but not a standard venture capital round; amounts not converted (several hundred million) are not included in the total, but actual activity is higher.
Three judgments from this issue's data:
- Embodied intelligence and robotics lead. The largest single round, Atoms' $1.7B, combined with Humanoid's $152M, makes Physical AI the largest capital magnet in the world.
- Chips and foundational layers are resurging. Etched's $300M (custom ASIC), Meshy's nearly $400M, and Memory Tensor (jointly invested by Huawei Hahuo), show that money is flowing toward computing power and generative foundations, which aligns with the domestic GPU's push to list in Hong Kong.
- Security and defense are forming groups. Glow's $180M, Cathedral's $160M, plus AegisAI, Abstract Security, and Zafran (Cisco's strategic investment), show that compliance and defense security are the third main line of capital this week that has been collectively highlighted.
Visit the SVTR official website (svtr.ai) or contact WeChat pkcapital2023 to access the full weekly report and project details.