

Main Focus This Week · Two Prices
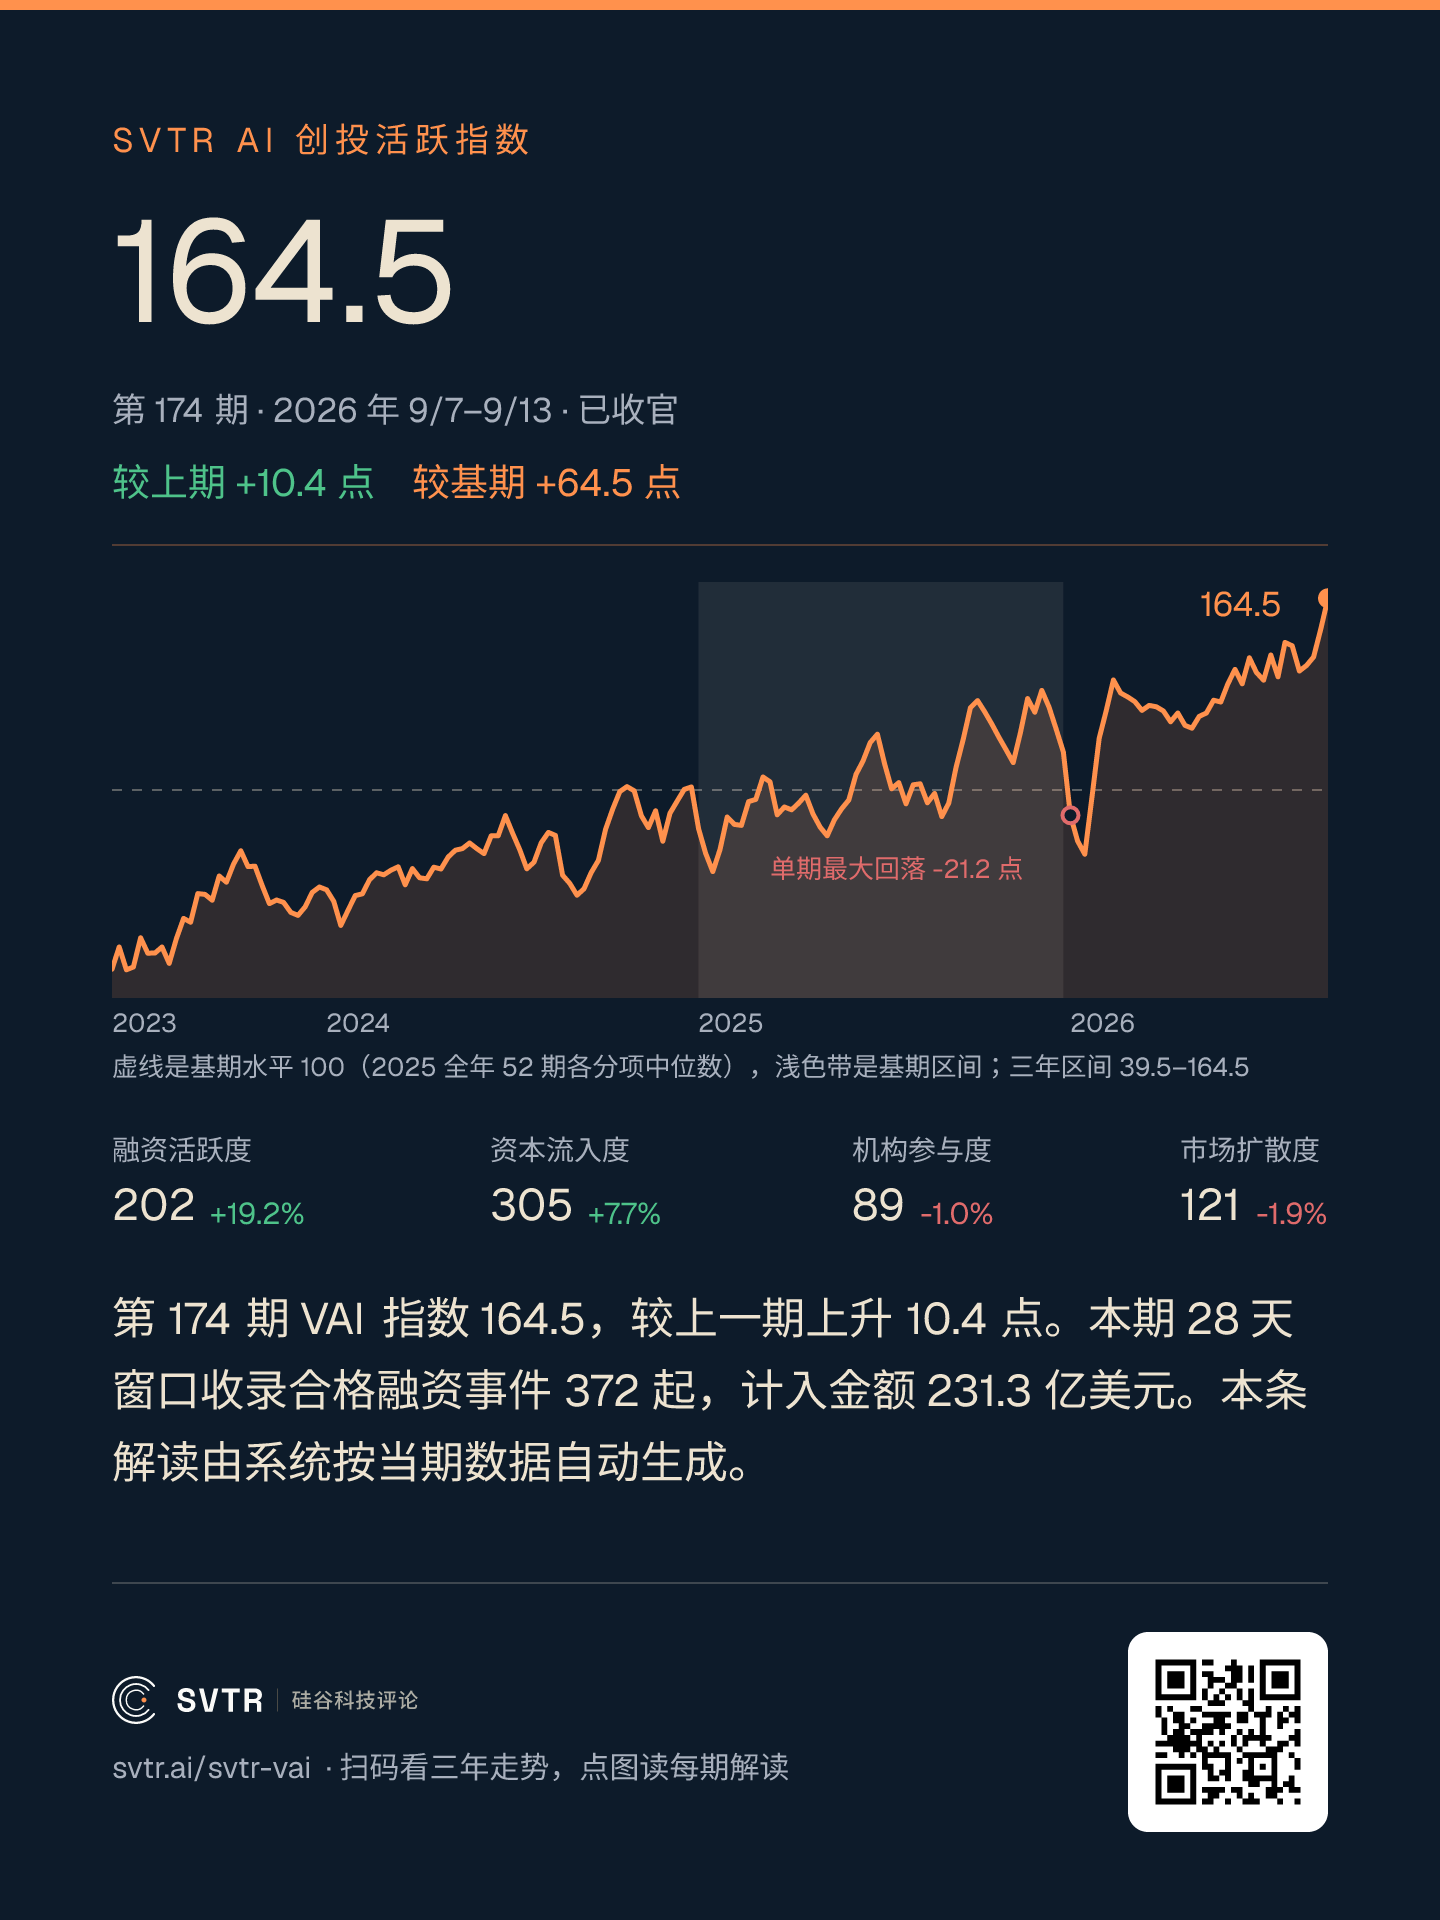
This week's SVTR AI Venture Activity Index is 164.5, up 6.7% from last week, setting a new high since its launch, 64.5% higher than the mid-2025 level. Among the four sub-indexes, financing activity rose 19.2% to lead, capital inflow rose 7.7%, while institutional participation and market diffusion fell 1.0% and 1.9% respectively. Among the 27 sub-sectors, transportation and logistics (+19.7%), developer tools (+14.7%), and vertical industries (+13.6%) led the rise, while defense and security ranked first in absolute value at 241.2. Optimization and evaluation (-17.0%), algorithms (-12.6%), and data (-10.0%) declined.
In the same week the index hit a new high, the most expensive acquisition of the week did not close: the $6 billion acquisition of Decart by Anthropic was terminated after due diligence. Meanwhile, AI programming company Cognition raised $2 billion at a $48 billion valuation, just four months after its previous round of $26 billion. The same set of assets received different valuations in the financing and M&A markets, and the two prices clearly diverged this week.
This week, the SVTR's AI venture database added a new "Recent Updates" section, and svtr.cn completed the article and event content pages.
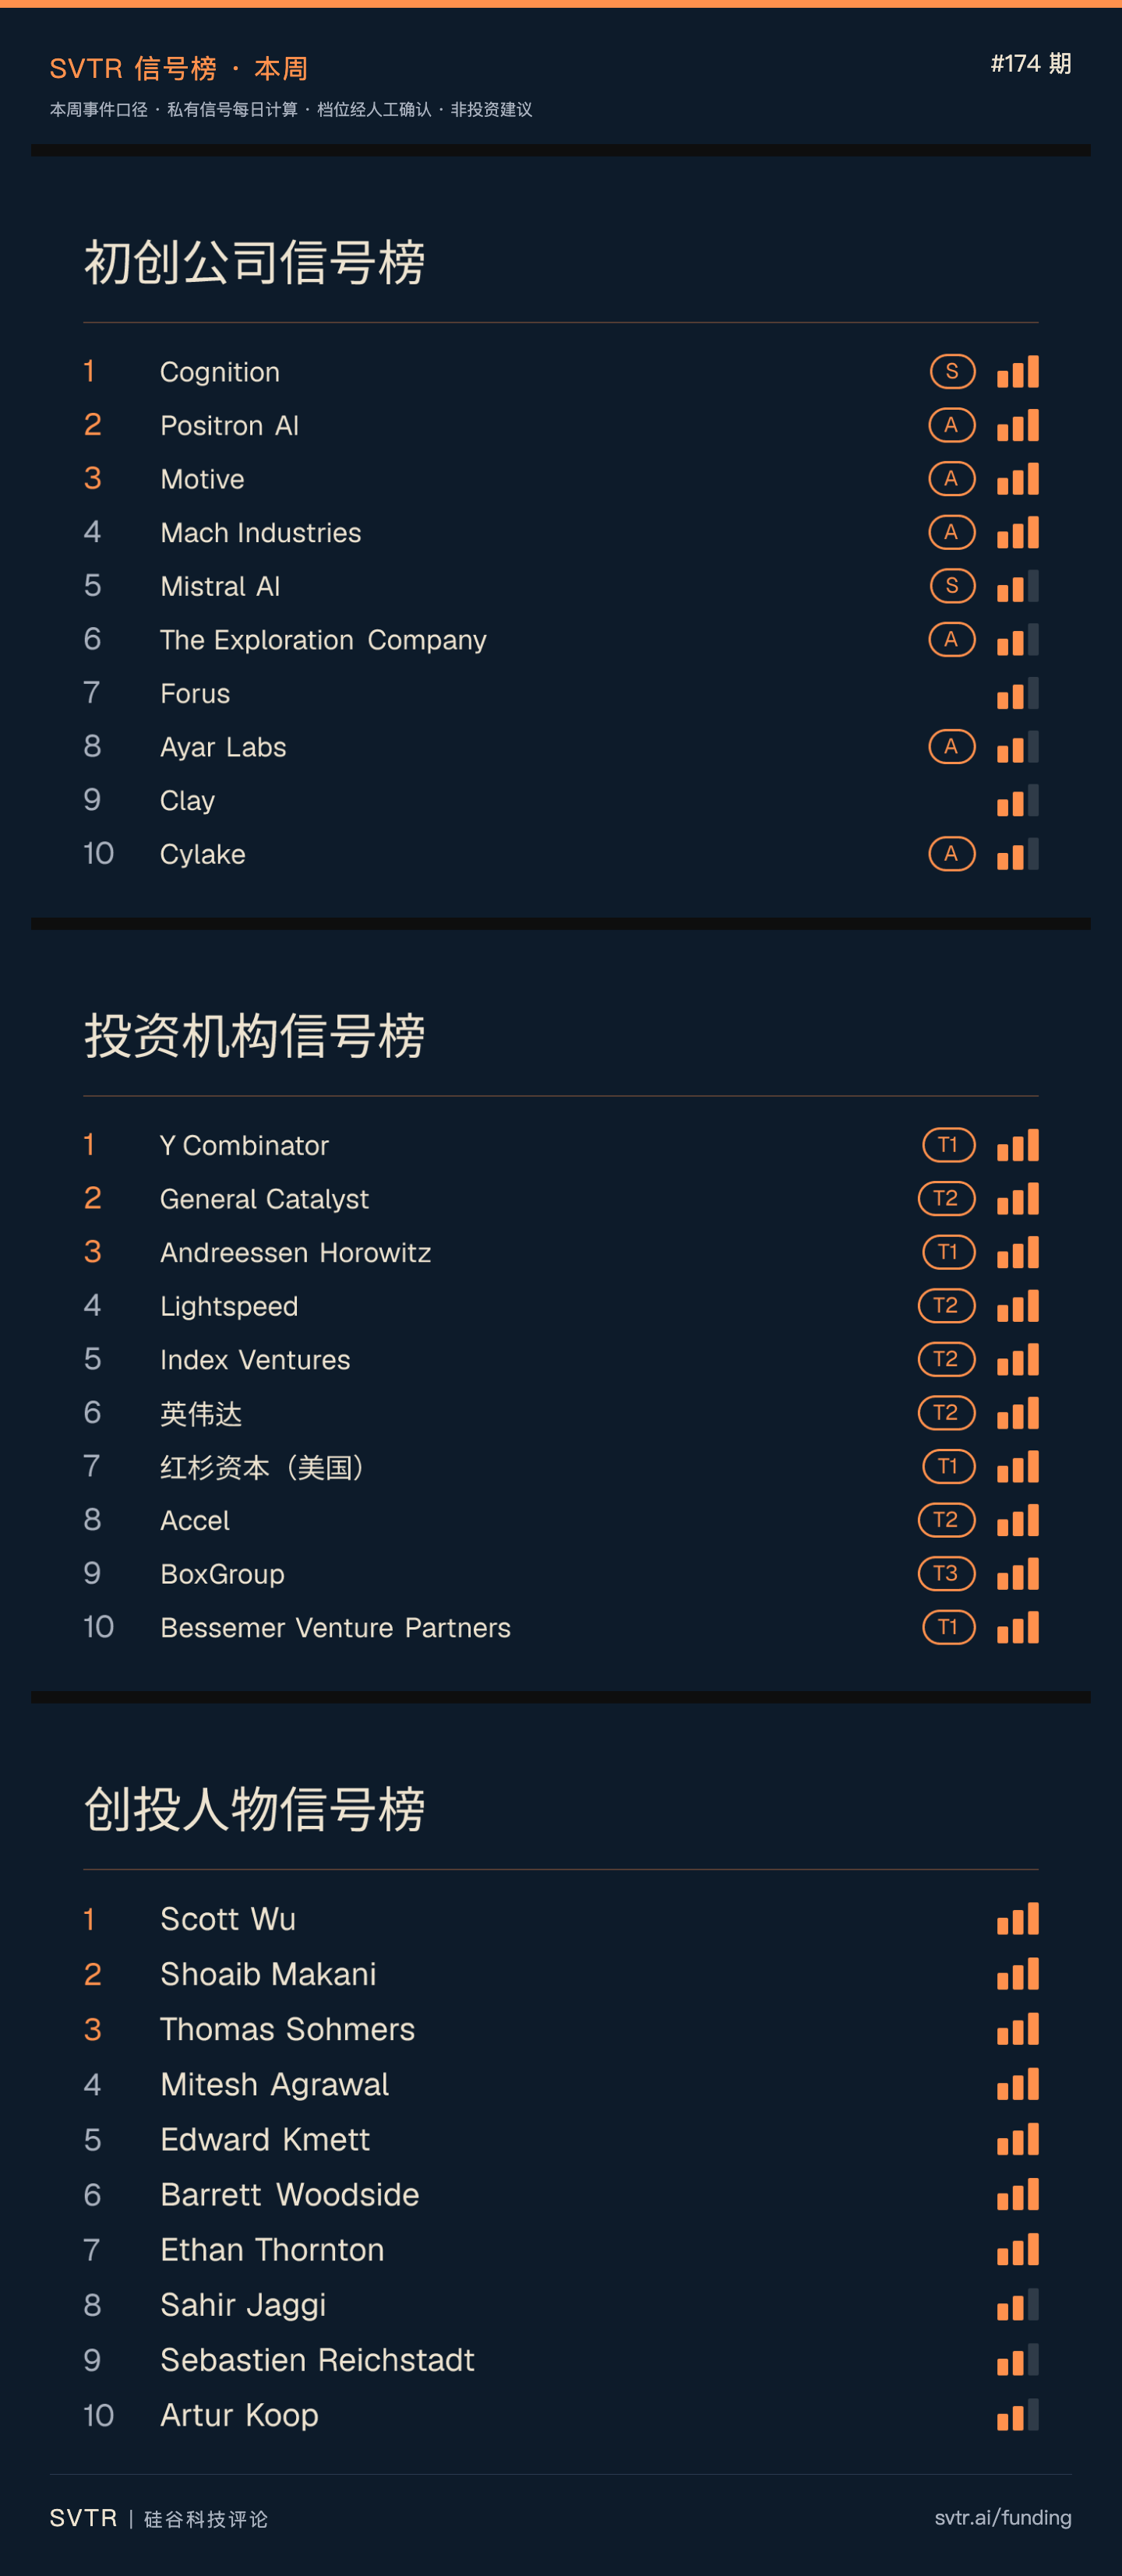
Full rankings are available in AI Venture Daily.
1. This Week's Opportunities
1. Financing and M&A
Salesforce is in talks to acquire Listen Labs for about $2 billion;
Grab is planning to acquire a majority stake in Atome Financial for over $2 billion;
Developer tools, which provide architectural intelligence to help developers understand and manage complex software systems, raised $1.1 million in Pre-Seed;
Controlled nuclear fusion, following the deuterium-tritium path, with a team having overseas research backgrounds;
Smart hardware, targeting family emotional companionship and health management, with the first AI toy already in mass production, raised several million yuan in Series A;
Enterprise services, building a brand visibility optimization platform on AI, raised between 50 million and 60 million yuan;
Chip design services, with a full-stack analog signal chain platform and over 120 self-owned patents, raised 200 million yuan.
A microLED optical interconnect company is raising its pre-seed round while seeking a CTO or engineering vice president-level technical partner.
2. Customer Collaboration
Two physical stores in the San Francisco Bay Area are opening automation pilot programs. One tea shop wants to introduce robotic arms to prepare drinks, and one self-service laundry wants to pilot clothing folding or sorting. The proposer is an operations team with experience in automation and retail operations, currently seeking a solution provider that can be implemented.
For more project details, please refer to the Selected Projects Library. Teams and institutions interested in connecting with us are welcome to contact us.
2. This Week's Analysis
The divergence this week is not about the amount of capital, but about the measuring stick used for valuation: the financing market buys growth curves, while the M&A market buys verifiable assets. Cognition's valuation doubled in four months, and its revenue also nearly doubled, so this round's valuation had business support. However, Anthropic's decision to walk away from a $6 billion deal after due diligence shows that the same company can be valued differently under the M&A measuring stick. The real information is not in the amount, but in the fact that a company with an extremely high valuation chose to exit when buying others.
Be cautious with the numbers in the M&A column. Three of the five deals this week have not been completed or are still under discussion. Only two deals have entered the formal transaction stage: Bending Spoons signed an acquisition agreement with Miro (enterprise value $1.355 billion), and Analog Devices signed a $1.35 billion cash acquisition agreement with Alif Semiconductor. Both have been signed but are still pending closing. Compared to the continuously rising valuations in the financing segment, the buyers in the M&A segment are clearly more cautious.
Meanwhile, five funds closed this week, totaling about $1.54 billion, making it the most stable of the three capital lines. The largest, Volition Capital Fund VI, closed at $950 million, exceeding the hard cap. Of the five, two were first-time funds, indicating that new GPs still received commitments this week.
In terms of sector indices, money is moving from 'statements' to 'tangible assets'. The top three declines were optimization and evaluation, algorithms, and data, all in the model and tool layers; the top three increases were transportation and logistics, developer tools, and vertical industries, with defense and security leading all 27 sectors at 241.2. Two of the top five financing deals this week were in defense and space hardware.
The investors are also changing. Two of the large deals this week were led by industry players rather than financial investors. Ayar Labs' $150 million round was co-led by AMD, Intel, NVIDIA, MediaTek, Alchip, and Wiwynn, almost covering all downstream customers of optical interconnects; Payward's $100 million strategic investment was led by Nasdaq Ventures.
Further Reading
How much a fund has made in the past does not determine how much it can raise this time (Signal): LPs no longer use historical returns as the basis for their commitments. The fact that five funds closed this week, including two first-time funds, is a real-world example of this article.
The valuation of AI4S starts to differentiate before results are available (Thesis): The scientific intelligence sector has already seen valuation differentiation based on team and platform capabilities before verification results are available.
AI booked a table for you, but the real challenge is getting it to pay for it (Recap): This week's AI venture meeting recap, the real bottleneck in completing the consumption loop with an agent is the payment process.
3. Market Signals
1. Startups
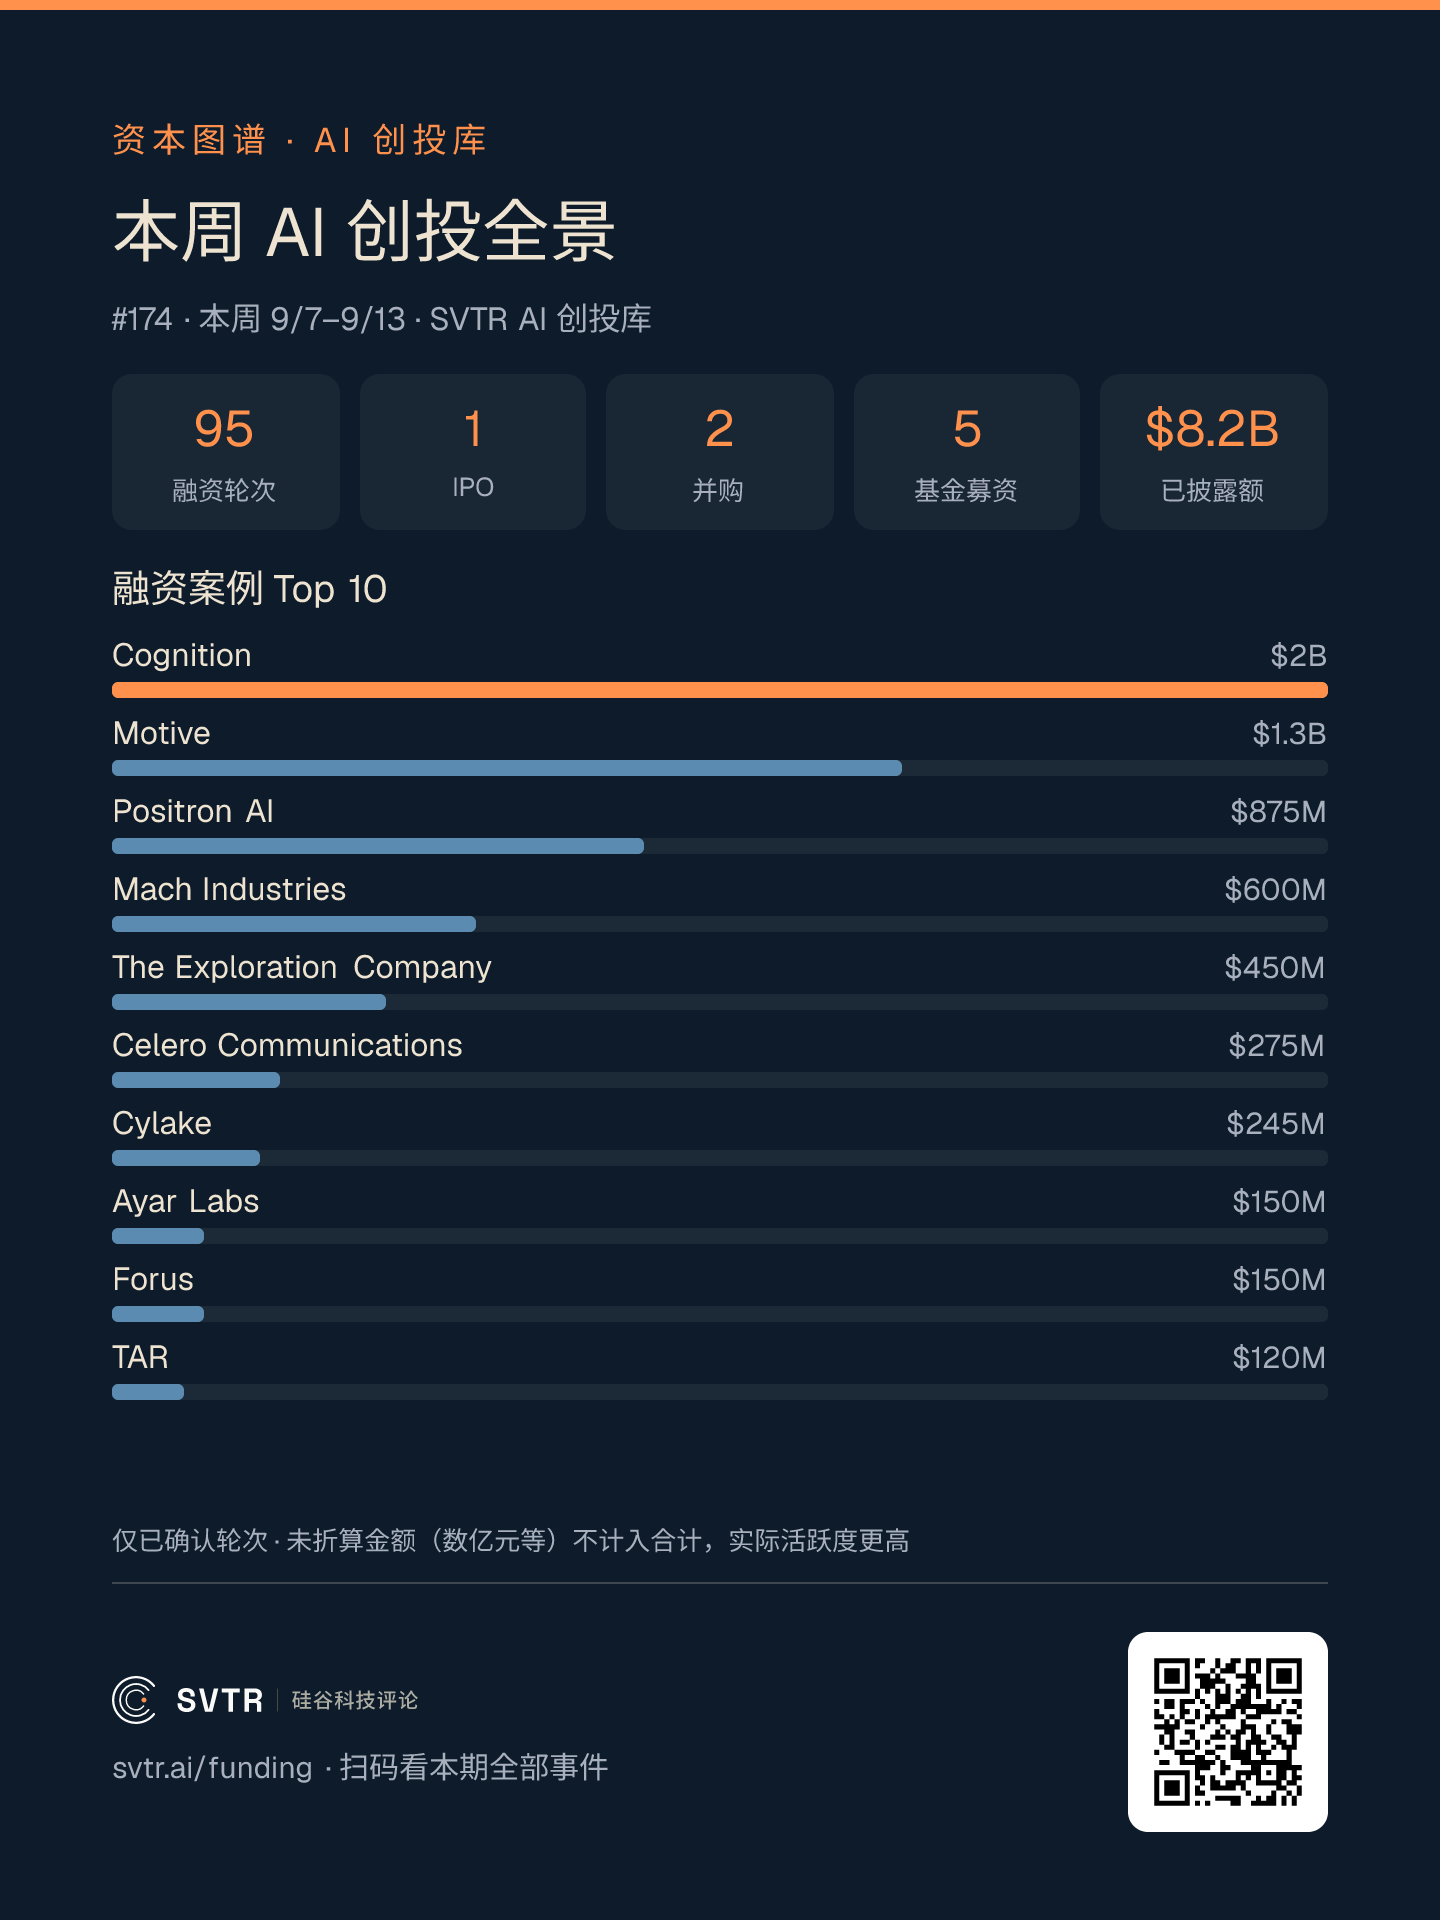
This week, 95 confirmed financing rounds were tracked, with about $8.2 billion disclosed. Early-stage rounds accounted for more than half, but the amount was concentrated in a few late-stage deals. Defense and space entered the top five, a new change this week: Mach Industries raised $600 million and The Exploration Company raised $450 million, totaling $1.05 billion, both targeting hardware delivery rather than model capabilities, which aligns with the absolute leadership of the defense and security sector. What is not visible on the chart is the status. The largest transaction this week, the $6 billion acquisition of Decart by Anthropic, was terminated after due diligence and not included in any statistics; Zixun Technology entered the Pre-IPO round, but the amount was not disclosed. There were more than 20 transactions in the Chinese market this week, with rounds mostly from pre-seed to Series B, and the full list is available in AI Venture Daily.
2. Investment Institutions
Five funds closed this week, totaling about $1.54 billion:
| Fund | GP | Size | Status |
|---|---|---|---|
| Volition Capital Fund VI | Volition Capital | $950 million | Hard cap closed, oversubscribed |
| LumaBio Fund I | Luma Group | $410 million | Committed capital |
| Wittington Ventures Fund III | Wittington Ventures | CAD 180 million | — |
| Clean Growth Fund II | Clean Growth Fund | GBP 81.5 million | Second closing |
| Rohati Fund I | Rohati Capital | $50 million | First-time fund |
Volition Capital's sixth fund targets growth-stage equity, focusing on tech companies with high capital efficiency and founder-led (including bootstrapped) in the US and Canada. Two of the five funds are first-time funds, indicating that new GPs still received commitments this week.
The capital structure itself is also a signal. The $150 million round for Ayar Labs had no financial investor leading, with the investors being AMD, Intel, NVIDIA, MediaTek, Alchip, and Wiwynn, almost covering all downstream customers of optical interconnects. Payward's $100 million strategic investment was led by Nasdaq Ventures. When industry peers and industrial players directly participate, it usually means that the technology has been regarded as a public infrastructure of the supply chain, rather than a competitive advantage of a single company.
3. Tech Giants
| Buyer | Target | Amount | Status |
|---|---|---|---|
| Bending Spoons | Miro | Enterprise value $1.355 billion | Final agreement signed, pending closing |
| Analog Devices | Alif Semiconductor | Initial consideration of $1.35 billion | Final agreement signed, pending closing |
On the side of the tech giants, only two deals entered the formal transaction stage this week. Bending Spoons' acquisition of Miro has signed a final agreement and is expected to close by the end of the fourth quarter, subject to regulatory approval. This company has always used the strategy of acquiring mature tool assets and reworking the cost structure, which is unrelated to the AI narrative. This week, it was the most certain deal. Analog Devices' acquisition of Alif Semiconductor targets edge-side AI chips, which is a move by semiconductor giants to complete terminal inference capabilities.
4. Event Preview
- September 14-15 | Imagination in Action will be held at Google Bay View in Mountain View for the Silicon Valley AI Summit. It covers AI infrastructure, agents, physical AI/robotics, AI for science, enterprise AI, venture capital, and frontier research. Confirmed speakers include: Astro Teller (X / The Moonshot Factory) Andrew Feldman (Cerebras) Ion Stoica (Databricks) Daphne Koller (insitro / Coursera) Daniela Rus (MIT CSAIL) Yossi Matias (Google Research) Marco Pavone (Stanford / NVIDIA) Rajesh Swaminathan (Khosla Ventures) and Stanford HAI, Google DeepMind, Anthropic, Salesforce, Foundation Capital, Qualcomm Ventures.

- September 19 | SVTR Frontier League #001: AI for Science, from Model to Discovery Scientists, entrepreneurs, corporate R&D, and investors will gather, with the lineup to be announced.

- September 20 | AI Makes Creativity Faster, Who Can Keep Up with the Speed of Commercialization? Guests from Starrtoy will discuss the IP and commercialization process.
Contact us via WeChat pkcapital2023 or visit svtr.ai to access the full weekly report and project details.