

Main Theme This Week · Money on the Way
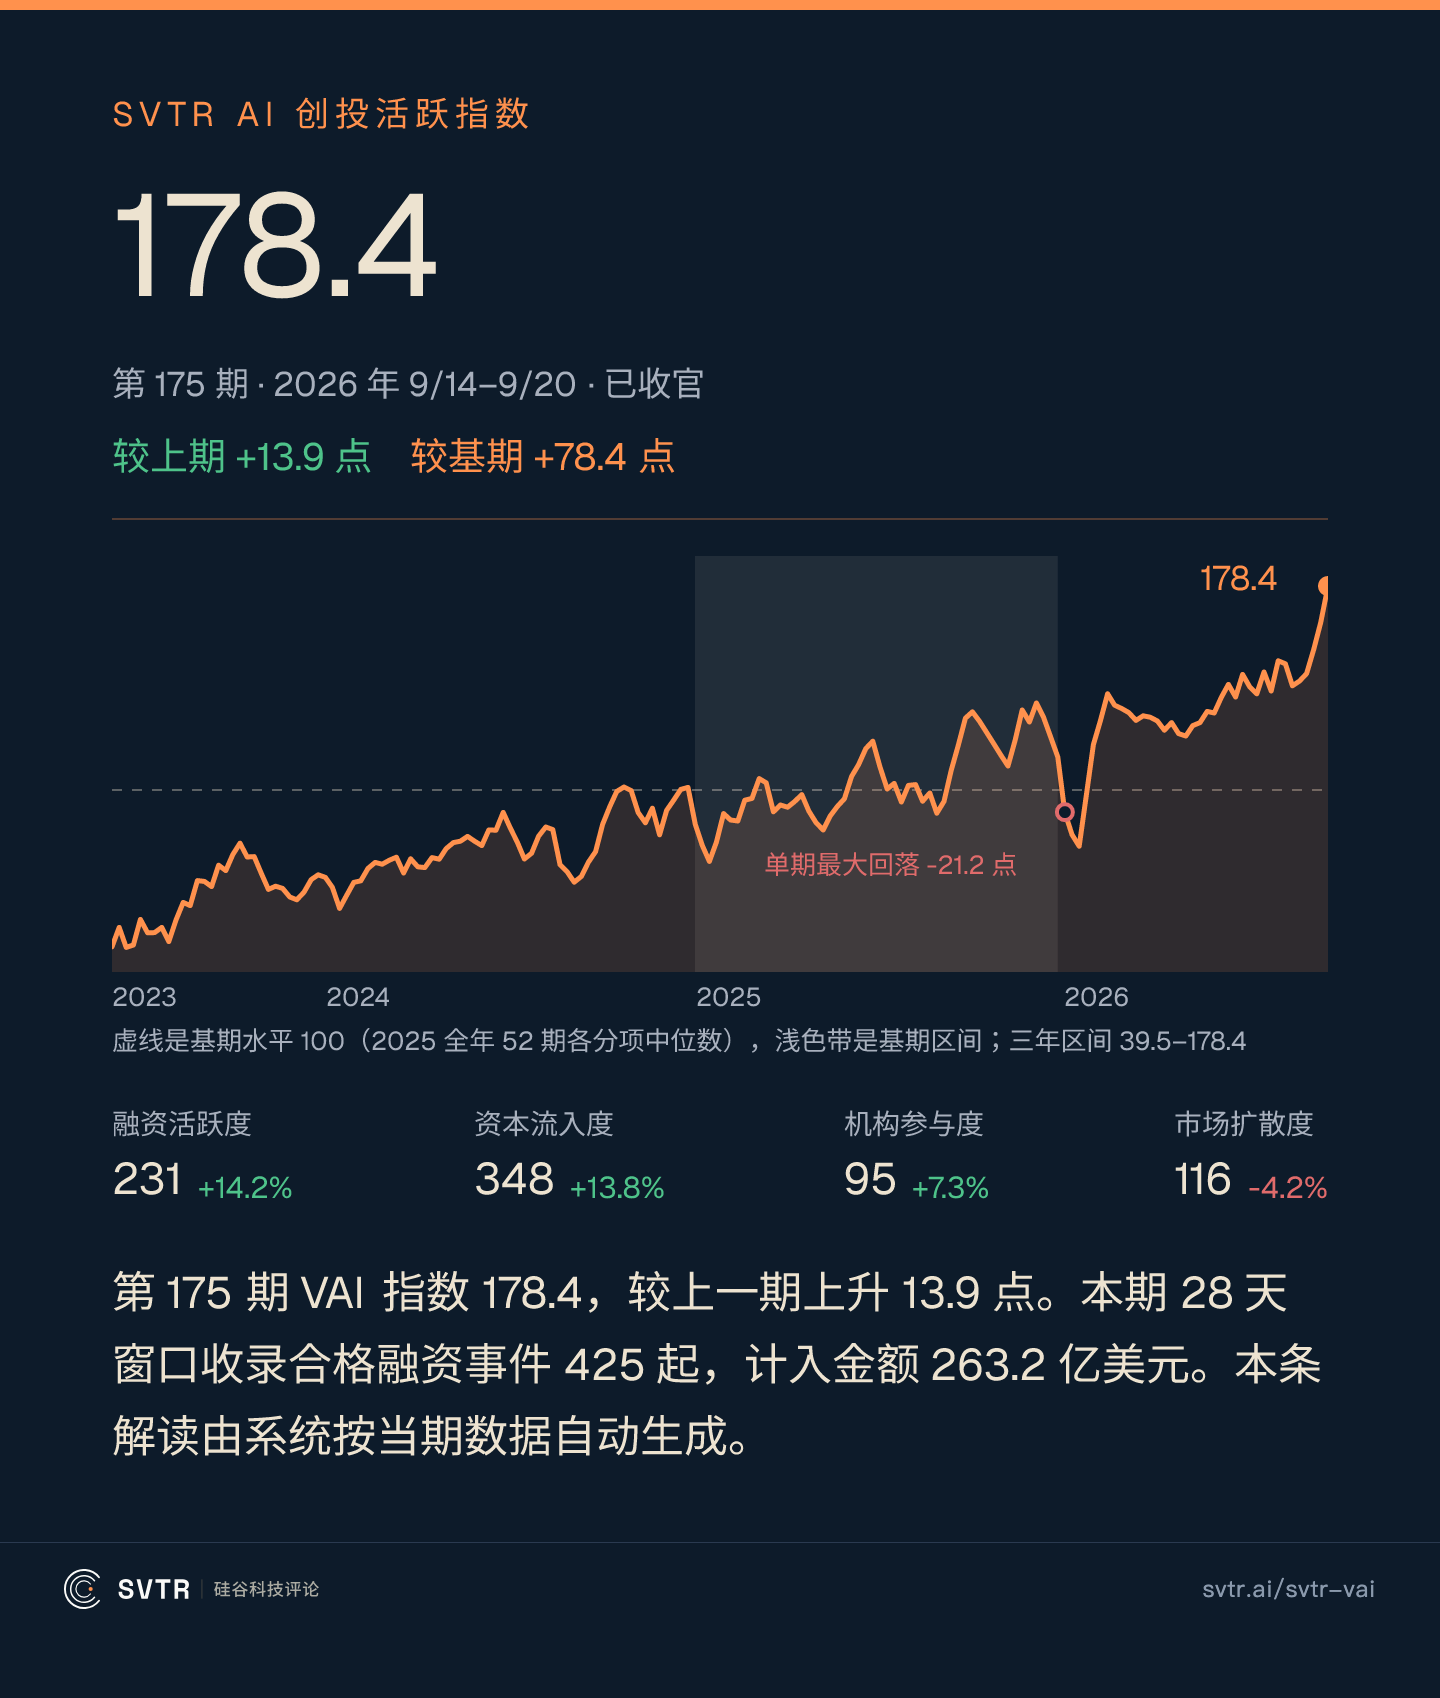
This week's SVTR AI Venture Activity Index is 178.4, up 8.5% from last week, setting a new record since its launch, 78.4% higher than the mid-2025 level. Among the four sub-indexes, financing activity rose 14.2%, leading the way, capital inflow rose 13.8%, institutional participation rose 7.3%, and market diffusion fell 4.2%. In细分 sectors, education and training (+25.7%), industrial manufacturing (+15.1%), and real estate technology (+13.4%) led the rise, while transportation and logistics (240.9) and defense and security (239.8) remained high, with vertical models and financial services slightly declining.
During the same week the index rose, the actual money that landed in companies' accounts actually decreased. This week, 116 confirmed financings totaled $5.5 billion, with no single deal reaching $1 billion, the largest being Temporal's $550 million. Meanwhile, 7 funds announced new fundraising rounds totaling about $9 billion, exceeding the money invested that week. Larger numbers are still on the negotiation table.
This week, SVTR's venture database allows users to search for investment institutions by investment focus and generate a ranking chart with one click. Additional content visible to members has also been launched.
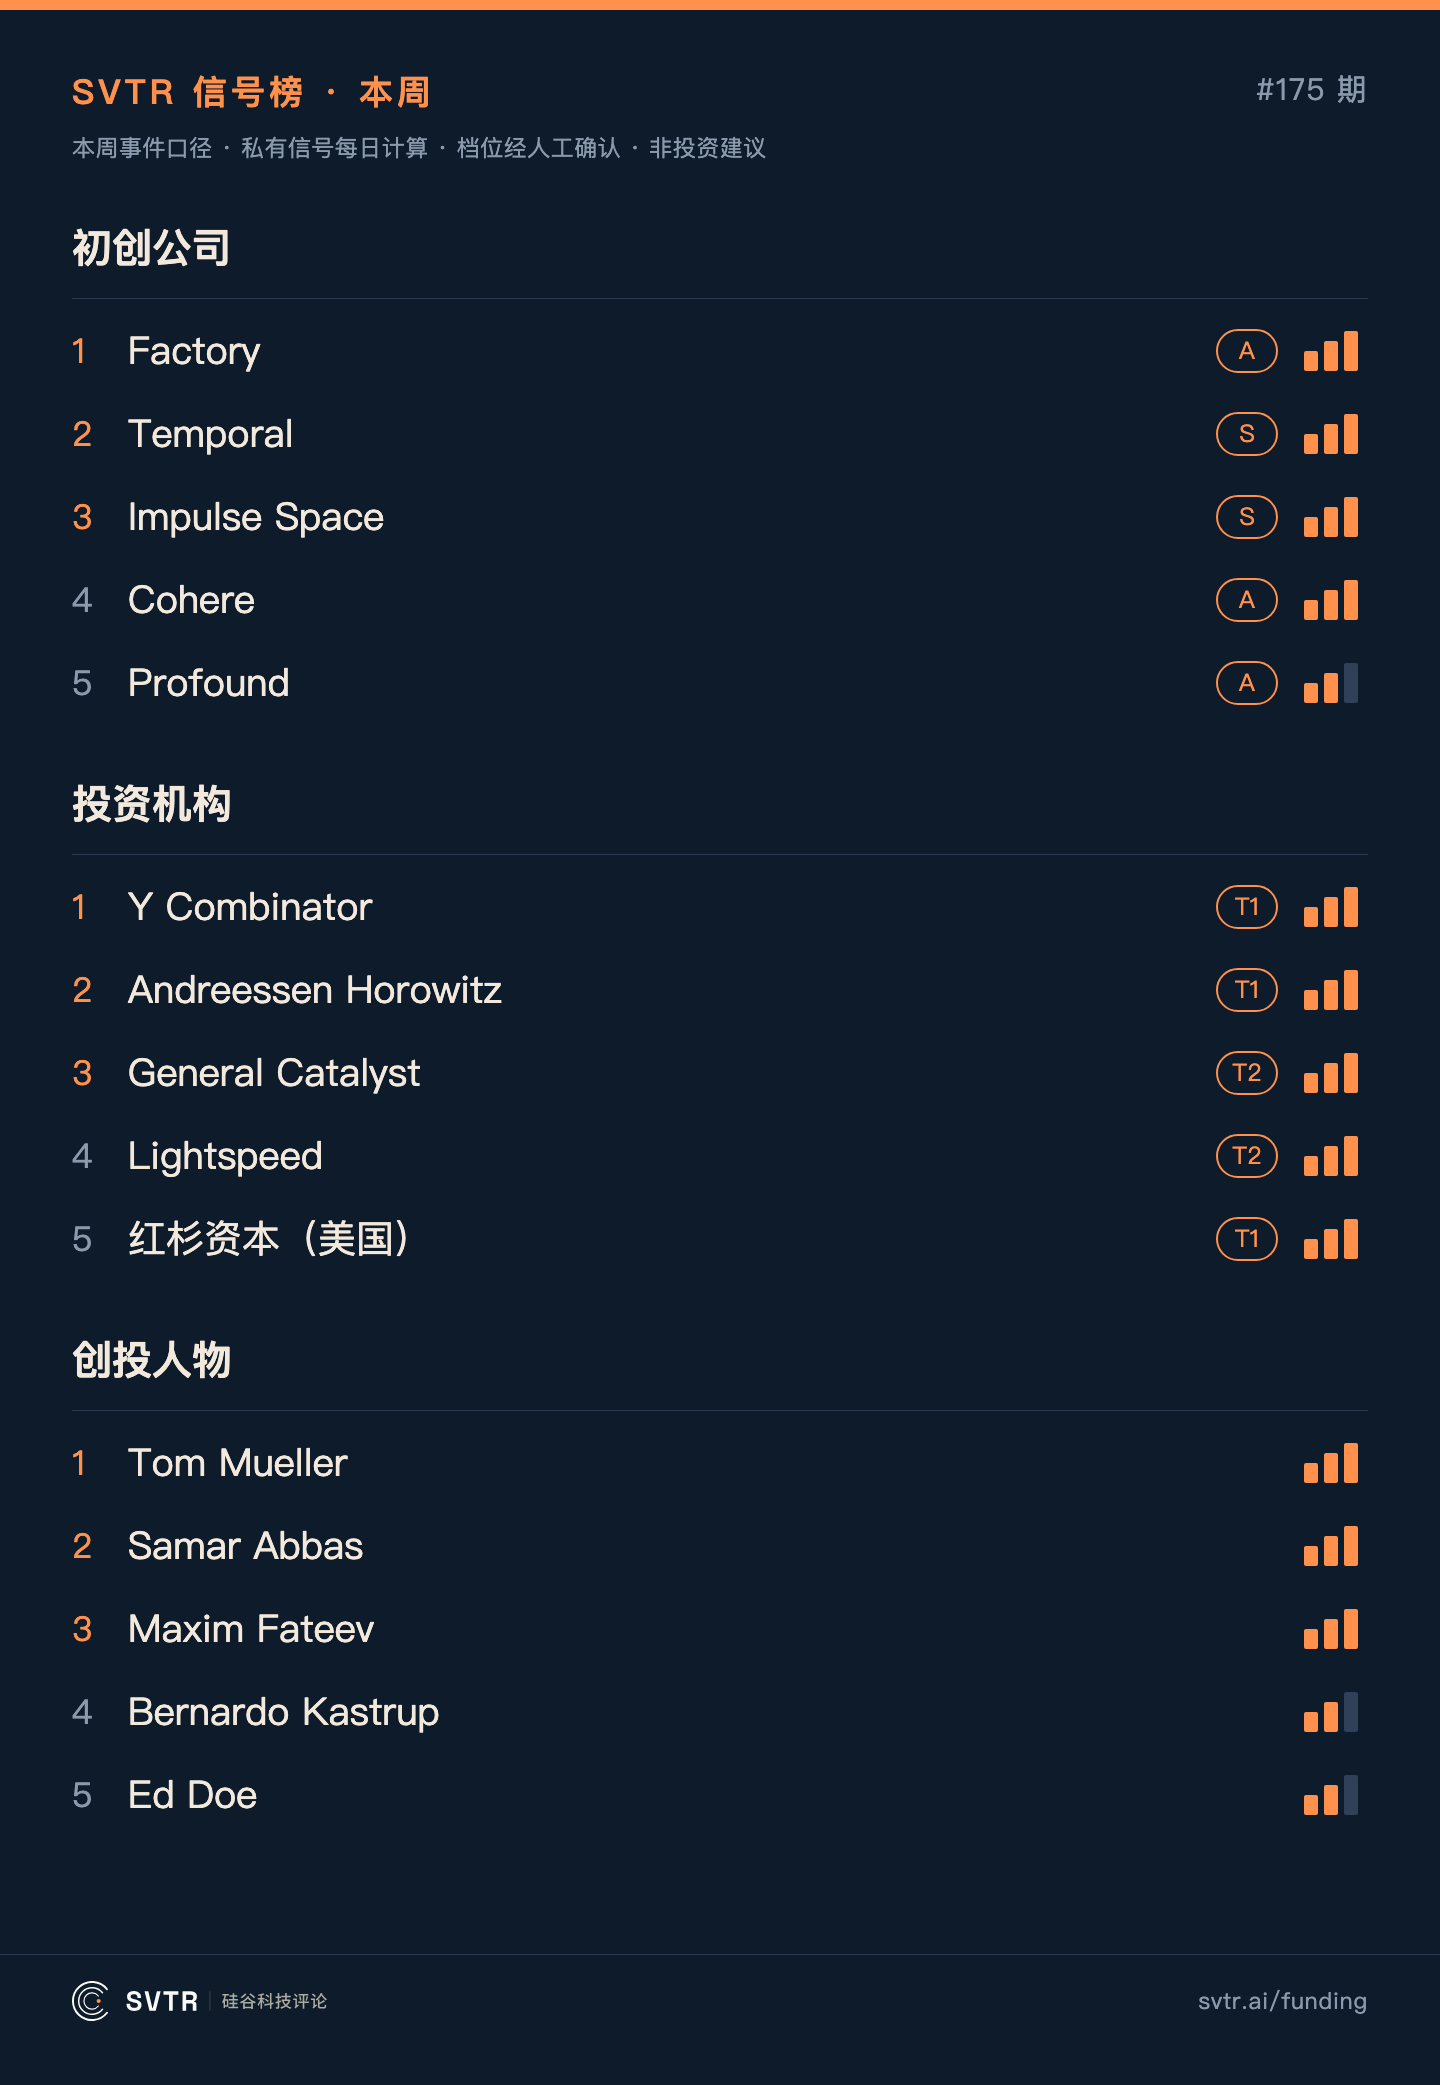
Full rankings are available in AI Venture Daily.
1. This Week's Opportunities
1. Fundraising and M&A
OpenAI is in early talks with investors about a new private funding round ahead of its IPO that would value the company at more than $1.2 trillion, according to Bloomberg, with the talks initiated by investors;
Firmus Technologies plans to list on the Australian Stock Exchange, with Bloomberg reporting it aims to raise about $5 billion, but has not yet submitted a prospectus;
Emulate, a company specializing in organ-on-a-chip technology, is in talks with Index Ventures and Lightspeed for a new round of funding of up to $700 million, with terms still undetermined;
Angle Health has signed a $600 million financing round, with $200 million in new shares for Series C and $400 million in a tender offer for existing shares, with the company stating the deal will close later this month;
ElevenLabs is in talks with EQT's Scaleup Europe Fund for a financing round exceeding $500 million;
Manus AI is in talks for a new round of funding of about $500 million, with an estimated valuation of $4 billion;
Industrial manufacturing: Physical AI models for closed-loop control of manufacturing processes, serving industry-leading clients in the US and Italy, Series A;
Compute: Dual-use RF propagation technology, with 53 patents, and partners including DARPA and multiple branches of the US military;
Life sciences: A regulated virtual R&D platform for GLP report production and multi-party verification;
Vertical industries: A lightweight 3D digital twin graphics engine developed from the State Grid Research Institute, seed round.
2. Customer Collaboration
There are no new collaboration requests this week. The automation pilot projects in two San Francisco Bay Area stores (tea shop robotic arms, self-service laundromat clothing folding and sorting) from the previous issue are still seeking solution providers.
For more project details, please refer to the Selected Projects Library. Teams and institutions interested in collaboration are welcome to contact us.
2. This Week's Analysis
Most of this week's money hasn't landed yet: more money is being raised than invested, and the largest deals are still under discussion. 116 confirmed financings totaled $5.5 billion, the highest number of deals in the past six weeks, with the smallest average deal size. At the same time, 7 funds announced about $9 billion in new fundraising. Looking back at the 13th issue, only two weeks had fundraising exceeding investment, and the last time was when the MGX $500 billion sovereign fund alone supported it. This time, it's the result of seven regular funds combined.
The number of deals hit a new high, but the $1 billion deals disappeared. The number of financing rounds increased from 31 five weeks ago to 116 this week, but the largest deal this week was only $550 million, with the top ten totaling $2.89 billion, accounting for more than half of the week's total. The previous week still had a $2 billion deal from Cognition, but there were no $1 billion deals this week. The money hasn't decreased, but it's no longer concentrated on a single point.
The truly large numbers are still in the 'under discussion' column. Firmus plans to raise $5 billion, Emulate is discussing $700 million, Angle Health $600 million, ElevenLabs $500 million, and Manus AI $500 million. Any of these deals would exceed this week's largest completed round. The M&A side is also quiet, with only one deal between Cohere and Aleph Alpha entering formal agreement, and the amount was not disclosed.
Large rounds in Europe are backed by public funds. The over €200 million round for EUCLYD was led by Samsung and EQT's Scaleup Europe Fund, with additional participants including Denmark's Export and Investment Fund, imec.xpand, and Brabant Development Agency; Exein's $270 million round included the European Investment Bank Group and Germany's KfW Capital. ElevenLabs, currently in discussion, is also backed by the same EU-supported fund. The common point of these three European deals is not the sector, but the investors.
Further Reading
After four industries discussed their own AI, they all hit the same bottleneck: the system only stores the result, not the reason (Recap): On-site recording of the AI for Science scene, with the bottleneck of four industries converging to the same point.
The first thing AI in healthcare sold was not a new drug, but fewer forms to fill out (Signal): The money in medical AI first flows into administrative processes rather than drug pipelines.
Robots can't be sold, stuck in 'proof' and 'after-sales' (Thesis): The bottleneck for robot companies is not in technology demonstrations, but in two things after delivery.
When models become cheaper, what starts to become valuable? (Thesis): After the price of models drops, pricing power shifts to the cost per unit of outcome.
3. Market Signals
1. Startups
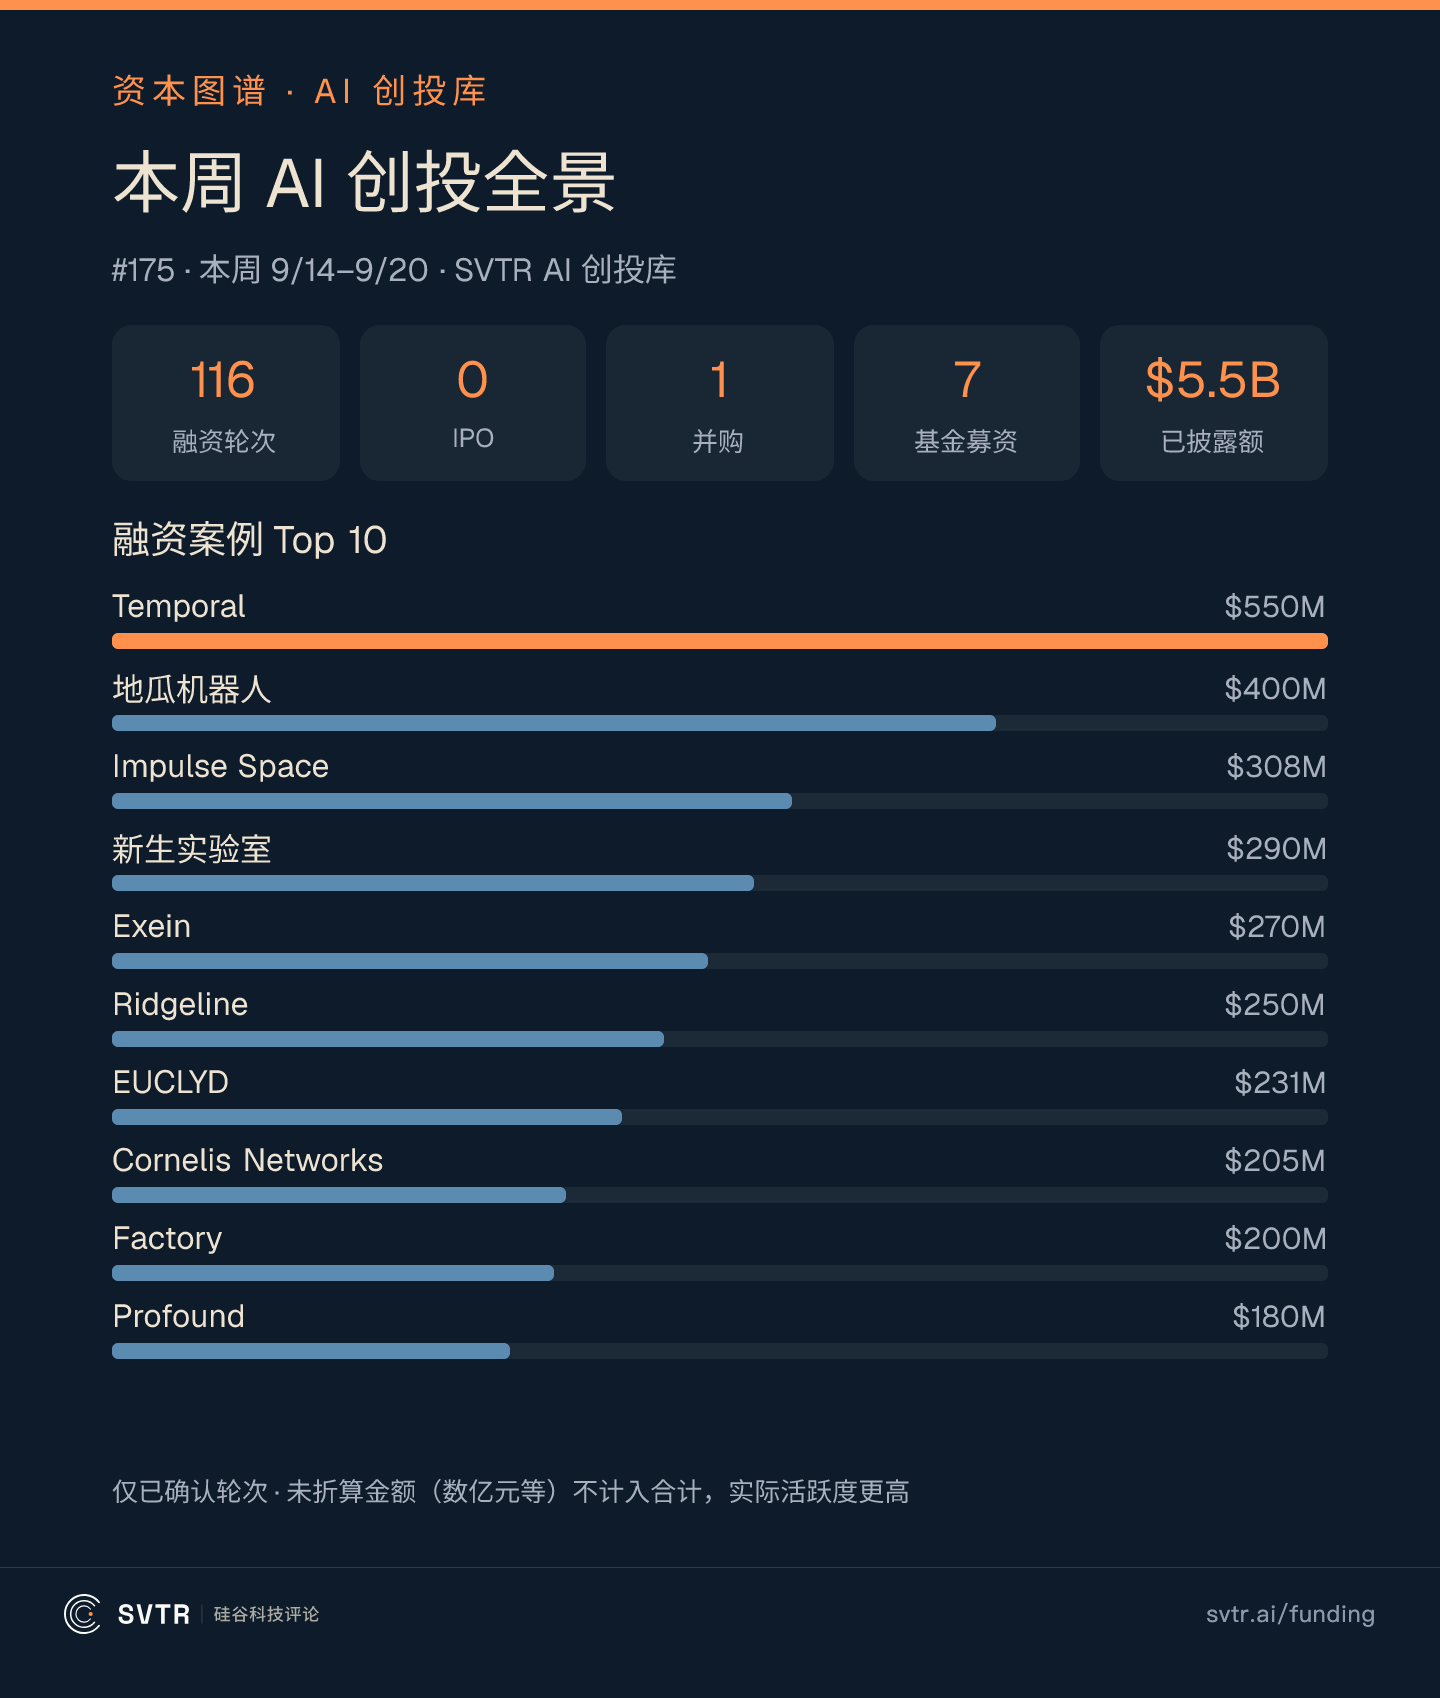
This week, 116 confirmed financing rounds were tracked, with about $5.5 billion disclosed, the highest number in the past six weeks, and the amount fell significantly from the previous week's $8.2 billion. Six of the top ten exceeded the $1 billion valuation line: Temporal raised $550 million at a $12.55 billion valuation, Factory raised $200 million at a $5 billion valuation, and Profound, Exein, Anew Labs, and Ridgeline were between $1.4 billion and $1.8 billion. The money is concentrated in this range, not higher up.
What's not visible on the chart is the status. Three IPOs listed this week are not valid: May Mobility has signed a merger agreement with a SPAC and is expected to close by the end of the year, Firmus is only in contact with investors and has not yet submitted a prospectus, and Plaud said it plans to file in 2028. According to the completed口径, there were zero IPOs this week. ByteDance's AI drug company, Anew Labs, completed a $290 million financing at a $1.5 billion valuation, and D-Robotics raised $400 million in Series C, the two largest deals in the Chinese region this week. The full list is available in AI Venture Daily.
2. Investment Institutions
This week, 7 funds announced new fundraising rounds totaling about $9 billion:
| Fund | GP | Size | Status |
|---|---|---|---|
| PSG Europe III | PSG Equity | 4.4 billion euros | Final close |
| Fund XI | Bain Capital Ventures | 1.6 billion dollars | Announced |
| Radical Breakouts Fund | Radical Ventures | Over 1 billion dollars | First close |
| Portage Ventures IV | Portage | 600 million dollars | Final close |
| Fund II | Matter Venture Partners | 450 million dollars | Announced |
| Ciena Ventures | Ciena Ventures | 200 million dollars | New fund |
| Pulse Fund | Pulse Fund | 63 million dollars | Final close, first fund |
This $9 billion figure needs to be analyzed. The growth equity fund PSG Europe III alone accounts for $5.1 billion, which is not classified as venture capital. Excluding it, the remaining six funds account for $3.9 billion, still the highest in the past 13 weeks, with the previous high being $3.5 billion in August. Of the seven funds, two are first funds, and one is a new venture capital department of the telecom equipment company Ciena.
There is another line on the funding side. The list of limited partners for Matter Venture Partners’ second fund of $450 million includes ASML, TSMC, Quanta, Nihon Shokui, and Japan's Policy Investment Bank, with the fund targeting semiconductors, robotics, and AI infrastructure. The direct involvement of industry players and policy banks as LPs indicates that this money is not only seeking financial returns but also visibility into the supply chain.
3. Tech Giants
| Acquirer | Target | Amount | Status |
|---|---|---|---|
| Cohere | Aleph Alpha | Undisclosed | Final agreement signed, pending regulatory approval |
On the tech giant side, there was only one deal entering the formal transaction stage this week. Cohere and Aleph Alpha signed a final agreement on September 16, and the merged entity will operate under the Cohere name globally. The financial terms were not disclosed, and the deal is expected to close this year. Both companies focus on enterprise-level large models, one based in Canada and the other in Germany, and the merger targets the same group of European and Canadian government and enterprise clients who are unwilling to entrust their data to U.S. cloud providers. Two other acquisitions were disclosed this week but not confirmed: Superhuman acquired the meeting recording tool Fathom, and OpenAI reportedly acquired the mobile imaging company Glass Imaging for over $300 million, although both parties have not officially confirmed the amount.
4. Event Announcements
- Afore Portfolio Fall Showcase
September 23, 17:00 PT | San Francisco, location will be informed after registration
Free, requires approval
SVTR Rating: 9.0/10
Afore Capital's portfolio company showcase, with participating teams all planning to start fundraising this fall, and partners from a16z, Accel, and Lightspeed on stage.
- TechCrunch Disrupt 2026
October 13-15 | San Francisco Moscone West
Paid, founder ticket $899, investor ticket $999
SVTR Rating: 8.3/10
Startup Battlefield 200 pitch competition and 300+ startup exhibitions, with a dedicated investor networking area.
- State of AI Report 2026 Launch Event
October 8, 17:30 PT | San Francisco, location will be informed after registration
Free, requires approval
SVTR Rating: 8.3/10
Nathan Benaich of Air Street Capital will present the ninth edition of the annual report on-site, with a discussion with Jamie Shotton, Chief Scientist of Wayve.
Contact us via WeChat pkcapital2023 or visit svtr.ai to access the full weekly report and project details.