
This issue · Chips for Inference
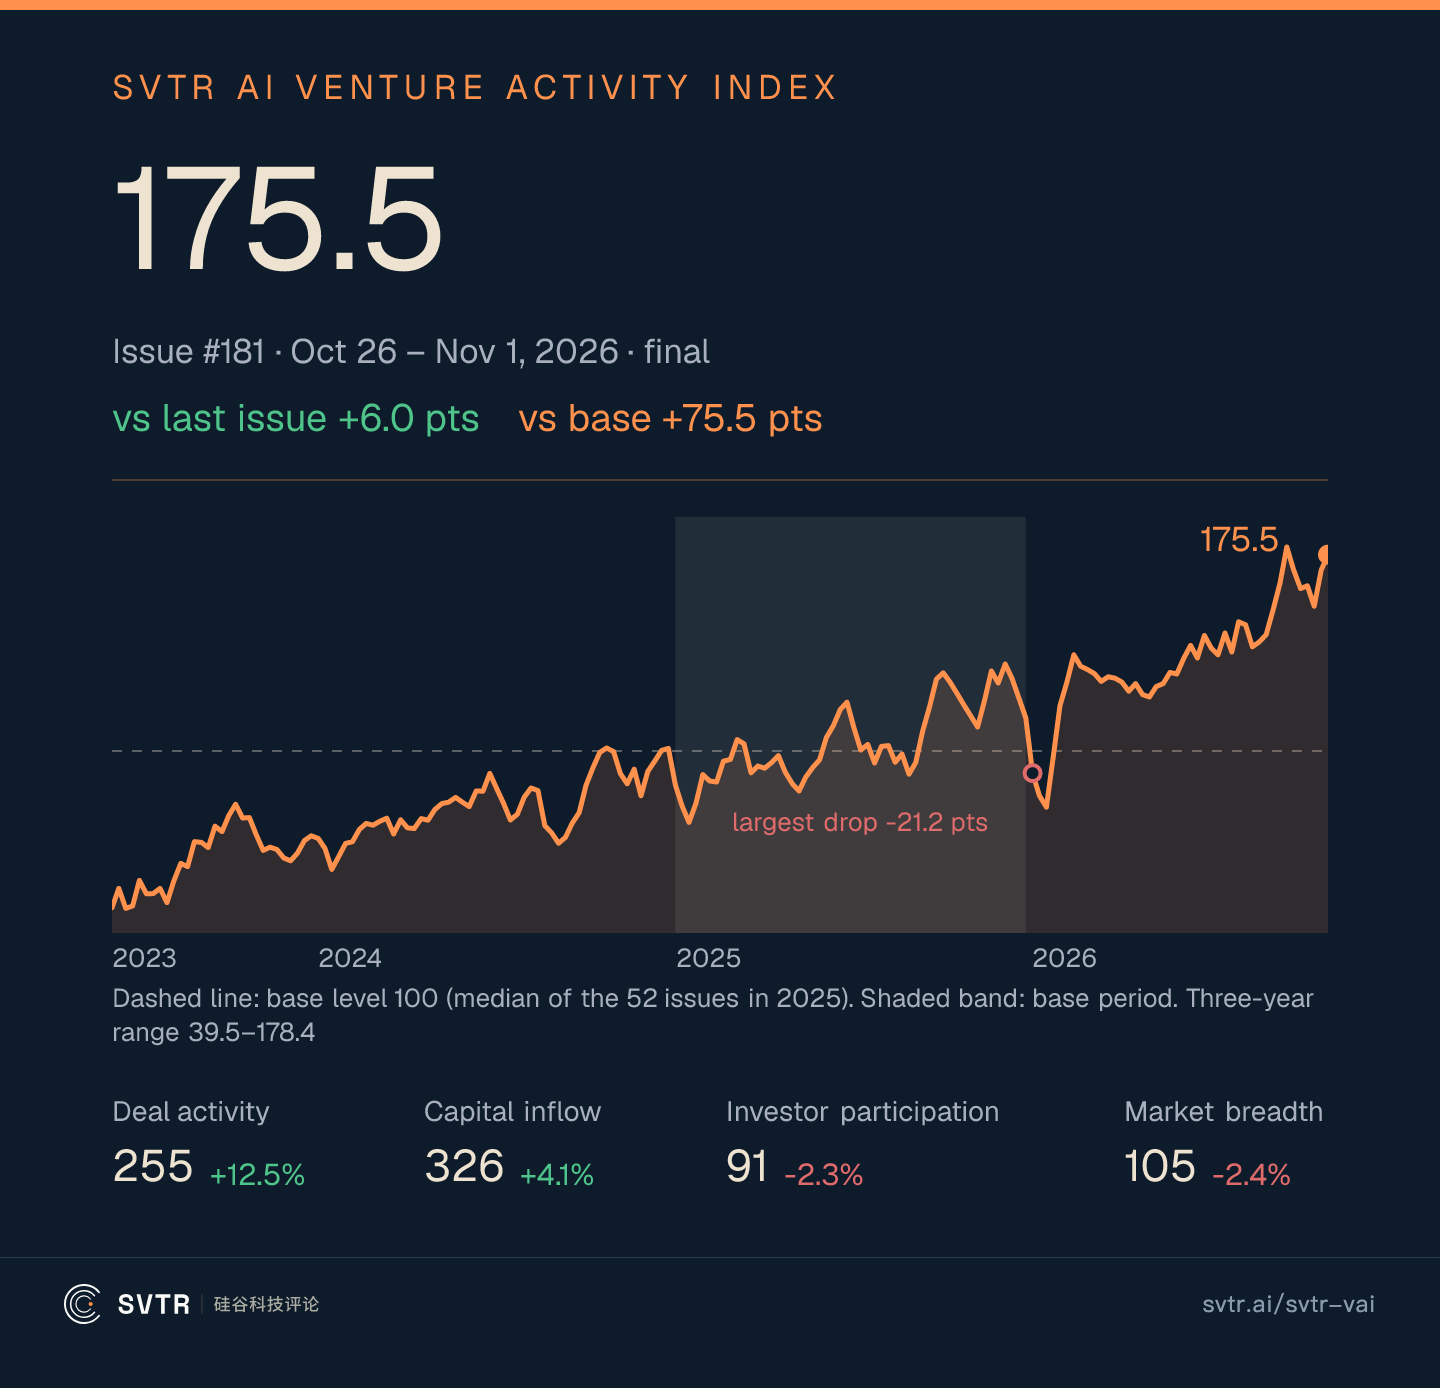
The SVTR AI Venture Activity Index rose 3.5% to 175.5 this week, 75.5% above its 2025 median level. Among sub-sectors, optimization and evals (+11.9%) and education (+11.8%) led the gains, while climate and sustainability fell 10.4%.
There were 119 confirmed rounds with $7.8B disclosed. Three inference chip companies raised $1.53B between them, about a fifth of the total and the most in any week since May.
New this week: AI Venture Rankings now has a city map; click a city to see funding details for the companies based there.
1. This Week's Opportunities
1. Financing and M&A
Table 1 | Issue #181: AI Deals in Progress
| Company | Deal | Terms |
|---|---|---|
| Baseten | Inference platform that deploys and runs models for companies; in talks on a two-tranche round led by Sands Capital | Size about $2B; valuation $26B, up to $30B in the second tranche |
| Physical Intelligence | General-purpose robot models; in talks on a new round led by Avenir and Lux Capital | Size at least $1B; valuation about $20B |
| Anthropic | Publicly filed its S-1 on October 26 for a Nasdaq listing under the ticker ANT | Size undisclosed; valuation undisclosed |
| Denglin Technology | GPGPU inference chips; Hong Kong IPO book open until November 5, listing planned for November 10 | Size about HK$1.48B at the midpoint; valuation undisclosed |
| Sarvam AI | Large language models for Indian languages; Cognizant in talks to join a Series B extension | Size: about $300M for the full round; valuation $3.5B to $4B |
| PowerLattice | In-package power delivery chiplets for AI processors; an SEC filing shows $86M sold in this round, and the company declined to comment | Target size $111M; valuation undisclosed |
| 22one | AI productivity tools for police forces, still in stealth; reportedly backed by Sequoia, General Catalyst, Lux Capital and Creandum, not yet announced by the company | Size undisclosed; valuation about $400M |
| upliance.ai | Smart home cooking appliances; in talks on a Series A, with existing investors including Khosla Ventures expected to join | Size $3M to $4M; valuation undisclosed |
| Holiday Tribe | Custom outbound travel from India, with AI itineraries plus human advisers; in talks with RPSG Capital Ventures and others | Size about $5.2M; valuation undisclosed |
| Mining robotics project | Raising; autonomous cleanup robots for underground mines that work around the clock without stopping production, with large mining customers | Size undisclosed; valuation undisclosed |
| Chip process project | Raising; AI models that understand fab physics design and run process experiments, shortening the path from lab to volume production | Size undisclosed; valuation undisclosed |
| Post-training platform project | Raising; Hangzhou team that mines user preferences from real usage logs and keeps training models with reinforcement learning | Size undisclosed; valuation undisclosed |
| Counter-drone sensing project | Raising; locates drones at the edge from optical signals, without relying on radio signatures | Size undisclosed; valuation undisclosed |
Data: SVTR Deal Showcase, as of 2026-11-01.
2. Customer Partnerships
Table 2 | Issue #181: AI Customer Partnership Requests
| Company | What it does | Looking for |
|---|---|---|
| Chip verification project | Uses graph neural networks to find the root cause of failed chip simulations | Chip teams willing to test it on production-grade designs |
| Clinical trials project | AI agents that organize source documents and transcribe data at clinical research sites | Research sites willing to pilot it |
| Chimeboard | Simulates consumer reactions before a marketing campaign launches | Brand customers |
Data: SVTR Deal Showcase, as of 2026-11-01.
2. Our Take
- Inference chips had their biggest week in six months. Fractile, FuriosaAI and NanoCoreChip raised $1.53B between them, and all three make chips only for inference (see Table 3). According to the SVTR AI venture database, inference chip companies had raised at most about $1.05B in a single week since May. The same week, Unconventional signed a deal to buy inference chip company NeuReality, and Denglin Technology opened its Hong Kong IPO. Our view: inference is billed by the token, so cost per watt goes straight into gross margin, and that gives non-GPU designs a market where the economics can be measured on their own. What matters next is how much of this hardware gets deployed in large customers' data centers.
Table 3 | Issue #181: Inference Chip and Inference Compute Rounds
| Company | What it does | Amount (valuation) | Lead |
|---|---|---|---|
| Fractile | UK; in-memory compute inference chips and systems | $774M Series C (reportedly $6.5B pre-money) | Reportedly Lightspeed, Redpoint |
| FuriosaAI | Korea; data center inference accelerators | $620M Series D ($2.9B post-money) | Undisclosed |
| NanoCoreChip | Hangzhou; 3D in-memory compute inference chips | Over RMB 1B Series C2 (undisclosed) | CCB Investment |
| General Compute | US; inference cloud on non-Nvidia specialized chips | $100M Series A (reportedly $800M post-money) | Blackbird, Abstract Ventures |
Data: SVTR AI venture database, as of 2026-11-01. Grouped by each company's main business; NanoCoreChip's round of over RMB 1B is counted as about $139M.
Holding companies that rebuild old businesses with AI are now buying public companies. Thrive Holdings, backed by Thrive Capital, had been buying small accounting and IT services firms; this week it signed a deal to buy home security company ADT at $10 a share, an enterprise value of about $15.3B. Our view: these buyers price a deal on how much labor AI can take out, and ADT, with about 6 million customers and 9 monitoring centers, is a business whose workflows can be broken down and costed that way. Whether margins deliver after closing will decide whether the model can be repeated.
Industry software leaders are paying business prices for AI-native peers. Guidewire signed a deal to buy insurance AI underwriting company hyperexponential for $1.7B in cash, and Itaú Unibanco agreed to buy NeoSpace AI, which builds its credit models, for BRL 2.925B. Last issue we wrote that AI-native application companies were mostly being bought at team prices; these two deals bought products already inside customers' workflows. Our view: software leaders in insurance, banking and law will pay full price for existing customer relationships, and that gives AI companies in these industries a clearer exit path.
Further Reading
- Canada Puts Up to C$1.6 Billion Into Cohere: State Anchoring Moves From Chips to Models (Signal): after Korea's national growth fund backed FuriosaAI, government money has moved from chips to models.
- After 21 VCs Turned Down Anthropic, Spark Bought In at SBF's Price (Thesis): the S-1 discloses the price of every round for the first time, matching Anthropic's IPO progress in Table 1.
- Inside Draper University Hero Training 33 Demo Day: the early-stage investment signals behind 36 startups (Recap): three of the community projects in Table 1 pitched at this demo day.
- The Ledger of 158,000 Startups: 88% of Founders Walk Away With Nothing (Thesis): even in successful exits, 19% of founding teams saw their stakes wiped out by protective terms in investment agreements.
3. Market Signals
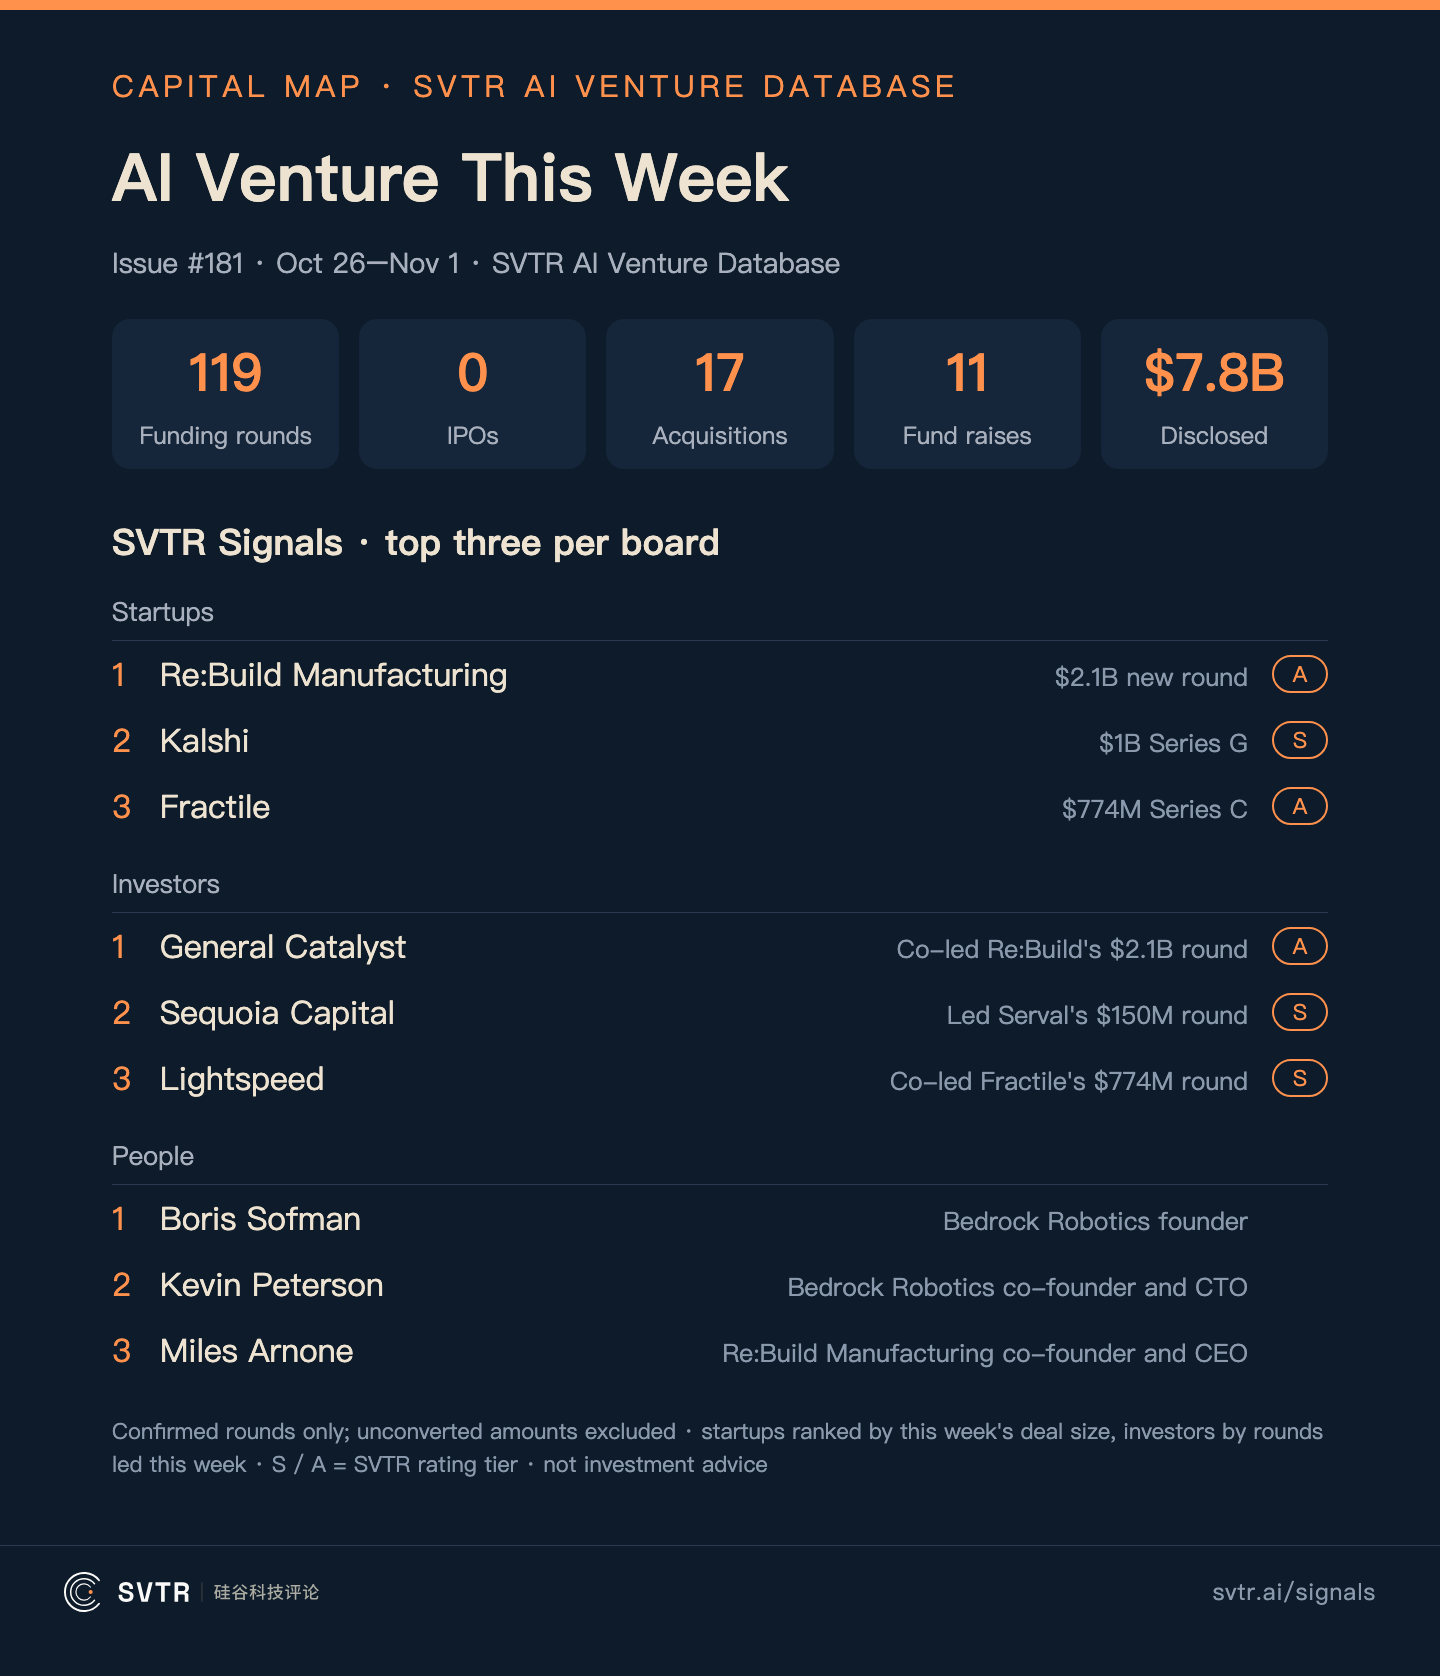
Full rankings on the SVTR Signal Board.
1. Startups
Table 4 | Issue #181: Top 10 AI Rounds by Amount
| Company | Business | Amount (valuation) | Lead |
|---|---|---|---|
| Re:Build Manufacturing | US industrial platform from design to volume production | $2.1B (undisclosed) | General Catalyst, JPMorganChase |
| Kalshi | US event contracts exchange | $1B Series G ($40B post-money) | Wellington, Sequoia |
| Fractile | In-memory compute inference chips | $774M Series C (reportedly $6.5B pre-money) | Reportedly Lightspeed, Redpoint |
| FuriosaAI | Data center inference accelerators | $620M Series D ($2.9B post-money) | Undisclosed |
| Bedrock Robotics | Autonomy retrofits for excavators and other construction equipment | $600M Series C ($4.1B post-money) | CapitalG, Emergence |
| Approaching.AI | Large model inference services | Over RMB 1.3B Series B (undisclosed) | Six co-leads including Zhecai Capital |
| Group14 Technologies | Silicon-carbon anode battery materials | €150M Series D extension (undisclosed) | Undisclosed |
| Serval | Automates IT tickets and access requests | $150M Series C ($3B) | Sequoia |
| NanoCoreChip | 3D in-memory compute inference chips | Over RMB 1B Series C2 (undisclosed) | CCB Investment |
| Dulo | AI foundation models for hardware design | $130M seed (undisclosed) | Undisclosed |
Data: SVTR AI venture database, as of 2026-11-01. Confirmed rounds only; Kalshi, Re:Build and Group14 are not AI-native companies.
Outside the table, Cohere completed the first close of its Series E at a C$35.7B post-money valuation, led by Schwarz Group with the Canadian government participating; the first-close amount was not disclosed and is not counted in the total. On the factory side, Foundry Robotics, which builds flexible assembly lines, raised a $100M Series A, and Lumaril, which tunes factory control systems, raised a $66M Series A. No AI company listed this week; see Table 1 for Denglin Technology's IPO.
2. Investors
Table 5 | Issue #181: AI-Related Fund Raises
| Fund | GP | Size | Status |
|---|---|---|---|
| Monolith Venture Fund III | Monolith Management, Beijing tech VC | Targeting $561M | SEC filing, no first close yet |
| New Mettle Capital fund | Mettle Capital, Series A and B in Indian tech | $350M | Announced |
| Nclude Fund | DPI Venture Capital, fintech and AI in Africa and the Middle East | Over $112M | Final close |
| Begin Capital Fund II | Begin Capital, AI infrastructure, hardware and chips | $100M | Launched |
| Entourage Fund II | Entourage, pre-seed and seed AI and deep tech | €100M | Hard cap reached within two weeks |
| Diffusion V3 | Diffusion, founded by former Benchmark investors | $70M | Announced |
Data: SVTR AI venture database, as of 2026-11-01.
3. Big Tech
Table 6 | Issue #181: AI M&A (Signed or Completed)
| Buyer | Target | Amount | Status |
|---|---|---|---|
| DoorDash | Instacart, same-day grocery delivery | Equity value about $17B | Signed |
| Thrive Holdings | ADT, home security | Enterprise value about $15.3B | Signed |
| Intel | Classiq, quantum application development platform | Reportedly about $2.2B to $2.3B | Signed |
| Guidewire | hyperexponential, AI underwriting and pricing for insurers | $1.7B cash, plus up to $400M contingent | Signed |
| Itaú Unibanco | NeoSpace AI, data foundation models for financial institutions | BRL 2.925B, paid in installments | Signed |
| CoStar | Vexcel, aerial imagery and geospatial data | About $730M, cash | Signed |
| Salesforce | Rune Technologies, military logistics forecasting and scheduling | About $375M, cash and stock | Signed |
| Unconventional | NeuReality, inference chips and servers | Undisclosed, cash and stock | Signed |
Data: SVTR AI venture database, as of 2026-11-01. DoorDash, Instacart and ADT are not AI-native companies; 9 more acquisitions had undisclosed terms.
Among the deals with undisclosed terms, Anthropic took on one-person biotech Mithril Medicine, whose founder had used Claude to coordinate 11 outside labs on rare-disease antibody research, and Deepgram acquired Daily, maker of the open-source voice agent framework Pipecat.
4. Upcoming Events
SVTR Spring 2027 Global Venture Camp · CES × Silicon Valley
Second round closes November 30
Camp planned for January 2027 in Las Vegas and Silicon ValleySVTR Saturday Salon
November 7, 15:00 PST | Palo Alto, California Ave
Apply in advance; SVTR verified members get priority1:1 with execs from OpenAI, NVIDIA, NEA, Cisco
November 14 | Brower Center, Berkeley
Paid, approval required
SVTR score: 9.0/10For pre-seed and seed founders: main-stage talks followed by small roundtables, with speakers including Cisco president Jeetu Patel and NEA partner Lila Tretikov.
Tech Weekend
November 19 to 20 | Menlo Park
Paid, two-day pass $1,990, some spots require approval
SVTR score: 8.5/10A two-day fundraising sprint with one-on-one investor meetings, a pitch competition and VC panels, listing more than 50 investors.
Note: visit SVTR (svtr.ai) for the full database and project details, or email us at kerry@svtr.ai.